Via Cernaia 3 - Follow on
- Interest rate
- 14% + up to 2% / year
- Payment
- Monthly
- End date
- Jun 30, 2026
- Invested
- € 97 697
- Loan to value
- 66 %
- Collateral
- Real estate mortgage
Reimbursement progress: 27%
1. Executive Summary
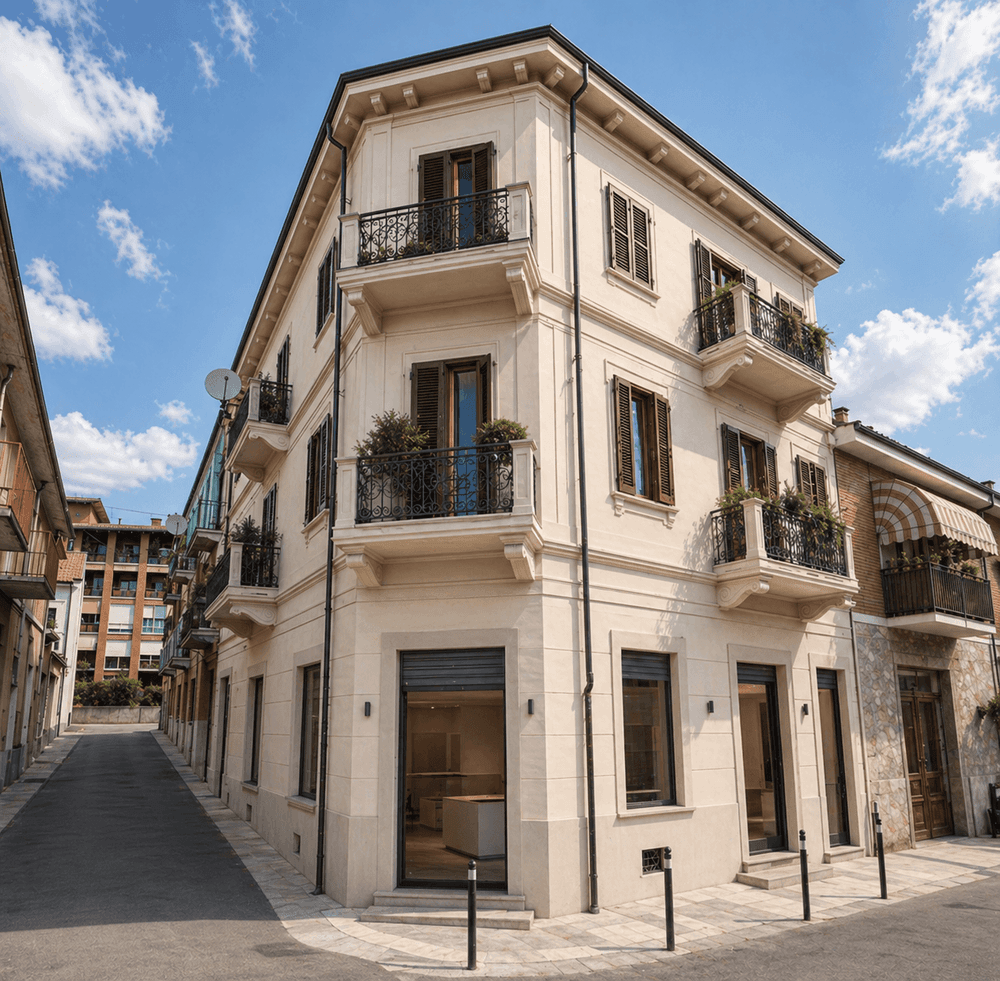
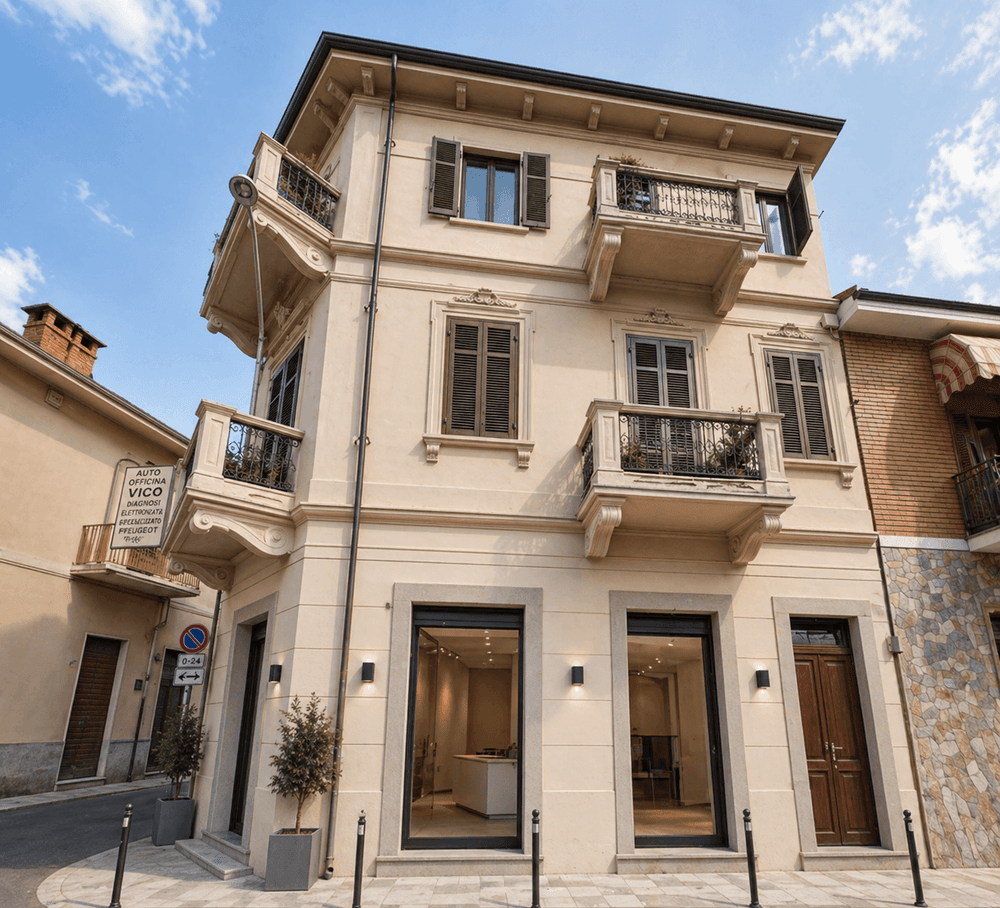
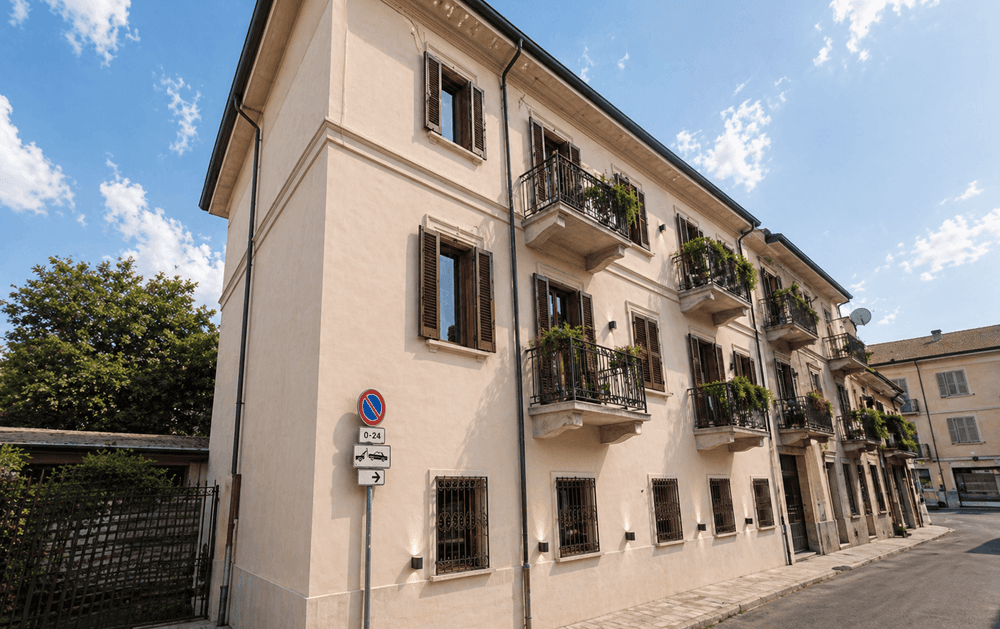
IBIMMOBILIARE SRLS is raising €445,000 on stock.estate to finalise the acquisition of a residential building at Via Cernaia 3, Moncalieri (TO), Italy, and to begin renovation works. The developer co-finances the acquisition with €200,000 of own equity and continues to fund the early renovation phase with additional own equity. The full project envisages a €1,200,000 internal renovation producing 14 residential units totalling 973.58 m², with a projected aggregate sale value of €2,377,123. The loan is 12-month duration, with monthly interest payments at 14.0% p.a. to investors (plus up to 2% cashback subject to stock.estate's promotional conditions) and bullet principal repayment at maturity, secured by a first-rank mortgage on the property covering at least 150% of the loan value, registered contextually with the acquisition deed.
2. Location Analysis
The property is located at Via Cernaia 3, Moncalieri, in the Province of Turin, Piedmont (north-western Italy). Moncalieri is a municipality of 55,923 inhabitants that borders Turin to the south and forms part of the metropolitan area, with direct access to Turin via SS393 and the rail line Turin-Genoa. The historic centre is dominated by the Castello Reale di Moncalieri, a former Savoy royal residence inscribed on the UNESCO World Heritage List as part of the Residences of the Royal House of Savoy, and Via Cernaia sits within the urban perimeter close to Piazza Vittorio Emanuele II and the medieval core. Three units in the project (units F1, D2 and E2) benefit from direct views of the Castle and the surrounding Turin hill.
The municipality is integrated with Turin's transport infrastructure (Lingotto and Porta Nuova stations within 15 minutes by car) and is approximately 100 km from the French border via the A32 motorway. Moncalieri's population has remained stable over the past five years, with rental demand growing materially: average asking rent rose from €7.92/m²/month in March 2024 to €9.10-€9.50/m²/month in August 2025, an increase of approximately +12-15% year-on-year.
3. Developer Profile
Legal entity: IBIMMOBILIARE SRLS, an Italian società a responsabilità limitata semplificata incorporated on 21 November 2023, registered at the Turin Chamber of Commerce under VAT/Tax Code 12967020012, REA TO-1329693, with registered office in Via Piero Gobetti 8, Orbassano (TO). The company's core business (ATECO 68.11.00) is the acquisition, renovation and resale of residential properties on its own account.
Sole director and shareholder: Iuliana Boghian, who operates a residential renovation business in the Turin metropolitan area and has previously delivered several apartment renovation projects in Turin. Her current operational portfolio includes another residential development in progress, reflected in the FY2024 balance sheet as €270,000 of inventory in finished and in-progress properties. The FY2024 accounts report revenues of approximately €430,000, total costs of €369,455, and a net profit of €60,544, the company's first full year of activity.
The company concentrates exclusively on the buy-renovate-sell business model in the Turin and Province area.
4. Project Overview
- Property type: Existing multi-unit residential building with full internal renovation
- Address: Via Cernaia 3, Moncalieri (TO), 10024
- Total commercial surface: 973.58 m² across three floors (Piano Terra, Primo, Secondo)
- Plot recovery: Approximately 220 m² of private garden/courtyard space
- Unit configuration: 14 residential units
- Piano Terra (3 units, 313.18 m²): 2 trilocali + 1 bilocale, all with private patio/garden access (subject to cambio d'uso from existing E0/C0/ex-box auto categories)
- Piano Primo (6 units, 341.76 m²): 5 bilocali + 1 monolocale, including unit F1 with terrace and Castle/hill view
- Piano Secondo (5 units, 318.64 m²): 3 bilocali + 1 monolocale + 1 trilocale (E2, with terrace and Castle/hill view)
- Ancillary spaces: 5 cellars (not included in the sales surface)
- Energy certificate: Pre-intervention class to be issued; post-renovation target Class A/B following full internal refurbishment
- Lift: Installation of new lift included in the renovation scope (executive design provided)
- Permits: Building already exists and is divided into apartments, so no major urbanistic permits are required. CILA/SCIA and cambio d'uso filings for the three ground-floor units (currently classified as ex-box auto and accessory commercial space) will be submitted within days of the acquisition closing; both are standard administrative procedures handled by the project architect (Arch. Lorenzo Da Ros, Albo TO n. 9417)
- Architect: Lorenzo Da Ros, executive plans dated 04/03/2026
- Expected completion: Within 12 months from acquisition
5. Market Analysis
The residential market in Moncalieri shows stable price levels with positive momentum. According to RealAdvisor (March 2026), the average price for apartments in Moncalieri is €1,841/m², with 12-month price growth of +3.1% for apartments and +3.8% for houses. Independent sources confirm the same range: idealista reports an average of €1,675/m² (August 2025) and Mercato-Immobiliare.info reports €1,750/m², approximately 1% above the provincial average of Turin (€1,720/m²) and 21% above the regional average for Piedmont (€1,440/m²). The rental market is structurally tight, with average asking rent rising +12-15% year-on-year to €9.10-€9.50/m²/month (August 2025).
Pricing rationale: positioning at €2,400/m² average against a municipal average of €1,841/m². The municipal average is a blended figure that includes the entire residential stock, predominantly older buildings, energy classes F-G, and properties in peripheral districts. The price spread within Moncalieri is wide and well-documented: 60% of apartments in the municipality trade in the range €1,240-€2,210/m² (Mercato-Immobiliare.info), and the upper-OMI quotations for the Centro Storico zone (Viale del Castello, Via Colombo, Via Alfieri) reach €2,015/m² (OMI) and €2,050/m² (FIAIP). The subject property is positioned within this Centro Storico perimeter.
Three structural factors justify the project's pricing above the upper-OMI ceiling:
- Energy class premium. OMI quotations are based on transaction data dominated by older stock (energy class F-G). Newly renovated apartments delivered in Class A/B typically command a +15% to +25% premium over comparable older stock in the same micro-location, reflecting both lower running costs and post-2030 EU energy compliance requirements.
- Product mix. The project is composed primarily of monolocali and bilocali (12 of 14 units), which are the smallest and most liquid formats in the local sale and rental market and trade at higher €/m² than larger units. The internal pricing reflects this: the lower-tier units (without view, on Piano Terra and Piano Primo) are priced at €2,160-€2,280/m², broadly in line with the upper-OMI Centro Storico ceiling, while only the four units with terrace and/or Castle/hill view (units F1, E1, D2, E2) are priced at €2,520-€3,120/m².
- Reference benchmarks. Renovated residential stock in adjacent Turin urban districts (Crocetta, San Salvario, Centro) trades at €3,000-€4,000/m². The subject property sits one tier below these benchmarks, supported by direct geographic proximity to Turin, the historical anchor of the Castello, and the residential character of Via Cernaia.
The blended €2,442/m² average sale price implied by the sales schedule is therefore consistent with documented Centro Storico ceilings, the post-renovation energy upgrade premium, and the unit mix.
6. Financial Analysis
| Item | Value |
|---|---|
| Acquisition cost (purchase price, ≈ €647/m²) | €550,000 + 80,000 |
| Renovation cost (turnkey, ≈ €1,232/m²) | €1,200,000 |
| Subtotal - direct project cost | €1,830,000 |
| Estimated cost of external financing (full-scenario, up to €1.0M facility over 12 months) | ≈ €200,000 |
| Total project cost | €2,030,000 |
| Projected aggregate sale value (14 units, avg ≈ €2,442/m²) | €2,377,123 |
| Projected net gross profit | €347,123 |
| Margin on total project cost | ≈ 17.1% |
The €445,000 raised in this campaign is the first tranche. The repayment of the stock.estate loan is sourced from progressive unit sales and/or refinancing as detailed in Section 7.
7. Funding and Investment Opportunity
| Parameter | Value |
|---|---|
| Loan amount (this campaign) | €445,000 |
| Maximum total external funding over the project lifetime | €1,000,000 |
| Developer equity at acquisition | €200,000 (plus additional equity for early renovation works) |
| Loan term | 12 months |
| Interest rate to investors | 14.0% p.a., plus up to 2% cashback subject to stock.estate's promotional conditions |
| Interest payment frequency | Monthly |
| Principal repayment | Bullet at maturity |
| Security | First-rank mortgage registered contextually with the acquisition deed at the notarial closing |
| Collateral coverage | Minimum 150% of the loan value. The acquisition is being executed at €550,000+80,000 against an estimated commercial value of approximately €750,000 for the building in its existing state, implying collateral coverage of approximately 168% of the loan value at closing |
| Disbursement mechanism | Funds released only at the notarial closing (no interim disbursement) |
Capital stack and funding plan. The €445,000 raised in this campaign, combined with €200,000 of developer equity, finances the acquisition (€550,000) + acquisition costs, fees, and taxes. (80,000). The early renovation phase is funded by additional developer equity. The remaining €1,000,000 required to complete the renovation will be sourced, in order of preference, from one of four identified channels:
- Progressive sales of finished or pre-sold units;
- Bank refinancing secured against the renovated asset;
- Additional developer equity;
- Follow-on stock.estate facility sized to maintain a maximum 66% LTV on the appreciating asset value.
Platform. The campaign is conducted by stock.estate, a European Crowdfunding Service Provider authorised by ASF (Romania) under licence PJR28FSFPR/400002, in accordance with Regulation (EU) 2020/1503 (ECSPR).
8. Risks and Mitigations
Market risk - A slowdown in Moncalieri's residential market could extend the sales timeline or pressure unit prices. Mitigation: the project is anchored to a Centro Storico location with documented upper-OMI quotations of €2,000-€2,050/m², supported by post-renovation Class A/B and a unit mix concentrated in the most liquid small-format segments. The 12-month price trend is positive (+3.1% apartments, March 2026), and only four of fourteen units rely on premium view-driven pricing.
Construction risk - Cost overruns or schedule slippage during renovation could compress margins or delay repayment. Mitigation: the works consist of an internal renovation of an existing residential building already subdivided into apartments, executed at €1,000-€1,200/m², within market parameters for this typology in Piedmont. Executive plans are completed (Arch. Lorenzo Da Ros), and the developer has prior renovation experience in the Turin metropolitan area.
Repayment risk - Repayment depends on the developer's ability to monetise the asset within the 12-month term. Mitigation: four independent repayment paths (unit sales, bank refinancing, additional developer equity, or a follow-on stock.estate facility at maximum 66% LTV on appreciated value). The projected net gross profit of €347,123 provides substantial cushion over the €350,000 loan, and the loan-to-cost ratio at this stage is approximately 18%.
Regulatory and permitting risk - CILA/SCIA and cambio d'uso for the three ground-floor units must be filed and approved before related works can commence. Mitigation: filings are planned within days of the acquisition closing, both procedures are standard administrative filings handled by the project architect, and the cambio d'uso targets the same residential destination already in place on the upper floors.
Funding-completion risk - The €445,000 raised here covers acquisition only; renovation completion depends on sales proceeds, bank financing, additional developer equity, or follow-on stock.estate financing of up to a further €550,000 within the €1,000,000 total external funding cap. Mitigation: the security mortgage protects investors regardless of subsequent funding outcomes; a partial or distressed sale of the building in its acquisition state at approximately the appraisal value (≈ €750,000) would already cover the loan principal with substantial residual margin.
Collateral and disbursement risk - The mortgage is registered contextually with the acquisition deed, and funds are released only at the notarial session, eliminating any interim period in which investor capital would be unsecured. The collateral coverage at closing is approximately 214% on the appraised commercial value, well above the 150% regulatory minimum.