Uni-steel IV
- Interest rate
- 10-16% / year
- Payment
- Monthly
- Time left
- 29 days
- Funding target
- € 682 752
- Precommitted amount
- € 582 752
- Loan to value
- 52 %
- Collateral
- Real estate mortgage
128 investors invested € 582 752
€ 582 752
€ 582 753
85.35% funded
€ 682 752
1. Executive Summary
UNI STEEL IMPEX S.R.L., a Romanian distributor of ferroalloys and metallurgical raw materials active since 1998, is raising a EUR 1,100,000 working capital loan over 24 months through the stock.estate platform. Uni-steel IV is a further public round of this financing: EUR 582,752 has already been subscribed by investors in the four previous public offers and is carried into this campaign as pre-committed capital, and this round seeks EUR 100,000 of additional funding, for a funding target of EUR 682,752. Subscriptions above the target are accepted on the same terms up to a maximum of EUR 200,000 of new funding, for a maximum value of the offer of EUR 782,752. The purpose of the financing is the expansion of the trading business: increasing inventory and financing an enlarged trade cycle in order to grow volumes with the company's certified suppliers and industrial clients.
Investors receive a progressive interest rate of 10% to 16% per annum, set according to the amount invested, in line with the rate bands displayed on this campaign page. Interest is paid monthly and principal is repaid in full at maturity, on 30.10.2028. The loan is secured by a first-rank mortgage, already registered in favour of stock.estate for EUR 1,650,000, over two properties: a luxury villa in the Herastrau area of Bucharest, Sector 1, independently appraised at EUR 1,716,000, and an apartment in the Amiral Constantin Bălescu area of Bucharest, Sector 1, evaluated at EUR 400,000. The combined collateral value of EUR 2,116,000 results in a loan to value of approximately 52% on the total loan facility of EUR 1,100,000 and collateral coverage of approximately 192%.
2. Location Analysis
The main collateral property is located on N.G. Caramfil Street no. 65, in the Herastrau and Nordului district of Sector 1, Bucharest, the capital's most established premium residential area. The street sits a few hundred meters east of Herastrau Park (King Michael I Park), the largest park in Bucharest, and within the Floreasca and Aviatiei corridor, the city's principal office and business hub. The Aurel Vlaicu metro station and the Promenada commercial center are within walking distance, and Henri Coanda International Airport is approximately 12 km away. The area concentrates embassies, corporate headquarters and high-end residential stock, and demand in this micro market is driven by the high-net-worth segment, both domestic and expatriate. Sector 1 consistently records the highest residential values in Romania, and the Herastrau and Nordului zone represents the top of that range.
The second collateral property, an apartment on Amiral Constantin Bălescu Street no. 20, Sector 1, Bucharest, sits in another well-established Sector 1 residential corridor. This adds a second, independent property to the security package, diversifying the collateral base beyond the single-asset exposure of the villa alone.
3. Borrower Profile
The borrower is UNI STEEL IMPEX S.R.L. (CUI RO10882264, J1998007797405, formerly J40/7797/1998), incorporated in 1998, with 27 years of continuous activity in the wholesale trade of metals and metal ores (main CAEN 4682).
Since 1998, the company has established itself as a reliable distributor in the metallurgical industry, acting as the link between certified producers and the complex requirements of steel mills and foundries. Its mission is to supply raw materials of the highest quality, ensuring full traceability and specialist technical support for every partner. The company specialises in ferroalloys and metallurgical raw materials (ferromolybdenum, ferrovanadium, ferrotungsten, ferrochrome, ferrosilicon), is certified ISO 9001, ISO 14001 and ISO 45001, imports from Belgium, the Netherlands and Colombia, and exports to Belgium, Germany and Italy.
The operating model rests on three pillars:
- It sources exclusively from certified producers, ensuring full traceability for every lot.
- It supplies not only raw materials but also consultancy on alloy selection, helping clients optimise their production processes.
- It reduces clients' operating costs through Just-in-Time deliveries and consignment stock management.
The company operates with a lean team and high productivity per employee, a structure typical of trading businesses. Its legal and fiscal standing is clean: no ANAF arrears, no insolvency records, and a history of fully repaid bank and leasing facilities. Company website: https://uni-steel.com/
Track record on stock.estate. This is a further public round for the same financing. The four previous public offers, uni-steel.com (closed on 30.06.2026 and 03.08.2026), uni-steel.com II (closed on 07.09.2026) and Uni-steel III (closed on 30.09.2026), raised EUR 582,752 in total from 128 investors; all interest instalments that have fallen due on those offers have been paid to investors. All investors in the public rounds rank equally under the same registered first-rank mortgage.
4. Collateral Overview
The security for the loan comprises three residential units across two properties, both located in Bucharest, Sector 1.
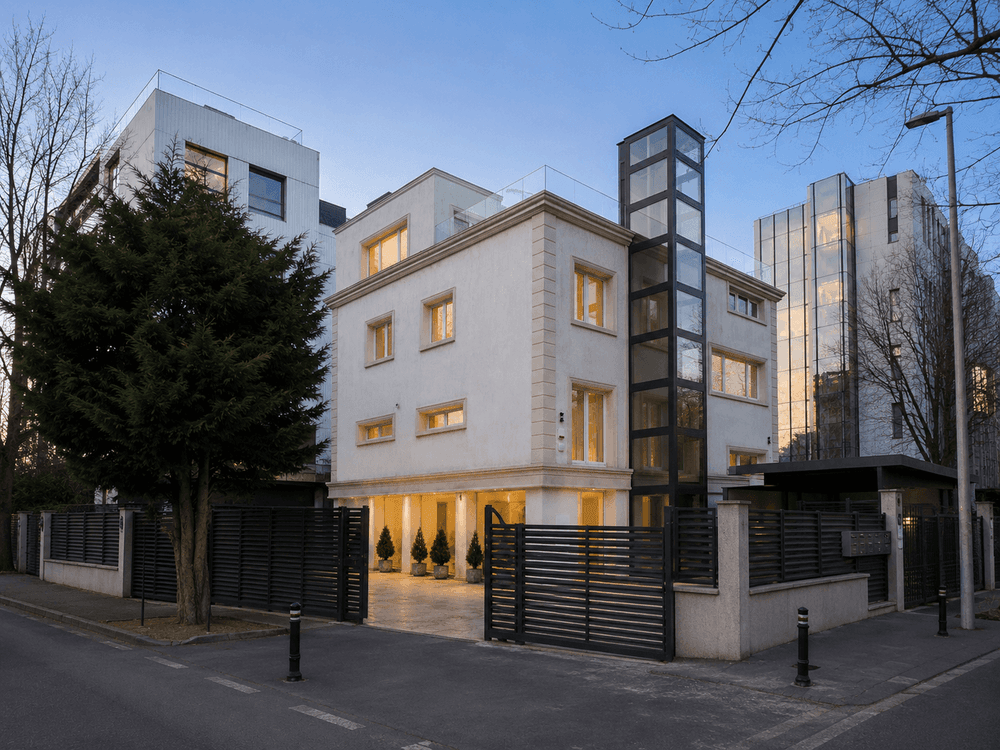
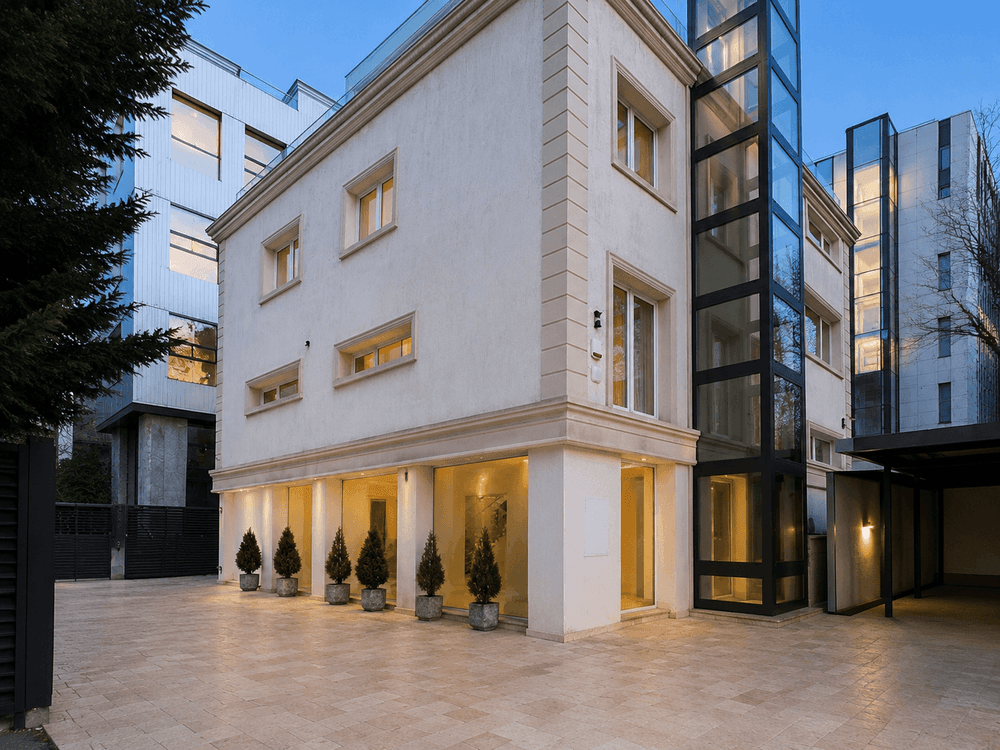
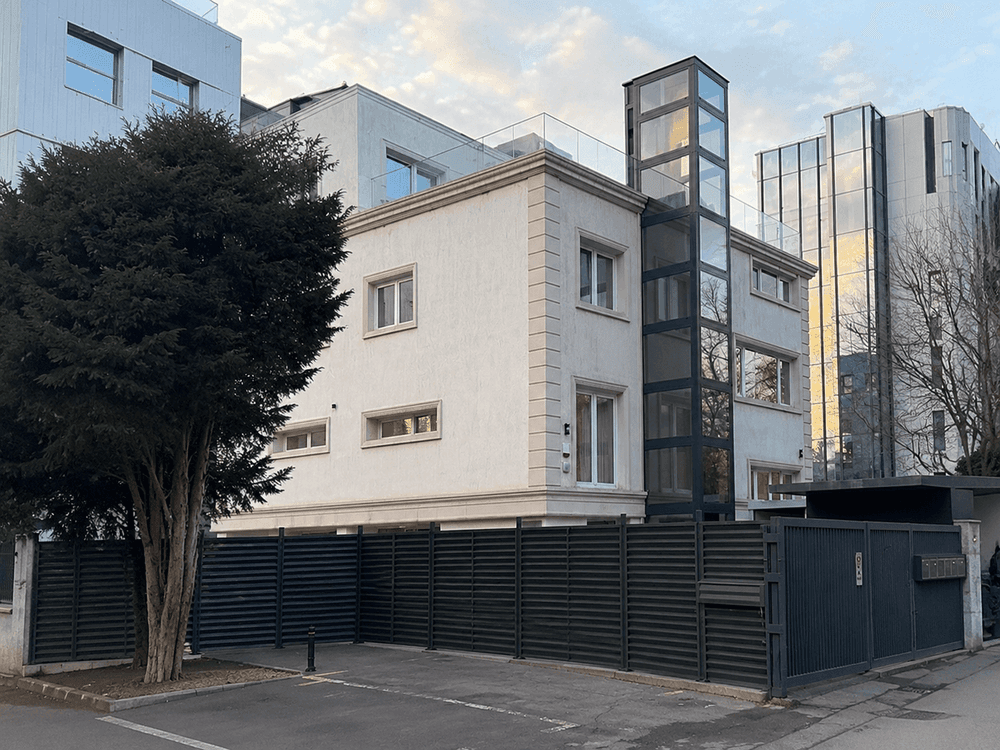
Property 1: Villa A (Caramfil)
- Location: N.G. Caramfil Street no. 65, Sector 1, Bucharest, in the Herastrau and Nordului district (the French Quarter).
- Type: detached luxury residential villa, reinforced concrete frame structure, built around 1996.
- Height regime: Ds+P+1E+2E (basement, ground floor and two upper floors).
- Usable surface: approximately 345 sqm.
- Features: superior finishes, lift, own thermal plant and parking.
- Cadastral structure: two units, together forming the entire villa and mortgaged as a single whole, together with the undivided land quotas and access shares:
- Apartment A1, CF / cadastral 255692-C1-U6
- Apartment A2, CF / cadastral 255692-C1-U8
- Valuation: independent ANEVAR appraisal (report commissioned by STOCKESTATE CROWDFUNDING SRL, dated 02.06.2026) of EUR 1,716,000.
Property 2: Apartment (Amiral Constantin Bălescu)
- Location: Apartment no. 2, Amiral Constantin Bălescu Street no. 20, staircase B, ground floor, Sector 1, Bucharest.
- Cadastral structure: CF / cadastral 252315-C1-U12, together with the undivided quota in the common parts of the building and the right of use over the underlying land.
- Valuation: evaluated at EUR 400,000.
Both properties are mortgaged in first rank in favour of stock.estate, already registered for a combined value of EUR 1,650,000, giving the loan security across two independent real estate assets rather than a single collateral position. The mortgages were registered before the first public round and secure all investors in the public rounds equally.
5. Market Analysis
The Herastrau and Nordului zone of Sector 1 is the highest-priced residential micro market in Bucharest, anchored by Herastrau Park, the embassy district and the Floreasca and Aviatiei business corridor. Asking prices for detached premium villas in this area sit well above the Bucharest municipal average, and the segment is supported by stable high-net-worth and expatriate demand. Liquidity for luxury villas is medium: the estimated sale exposure time is approximately 6 to 12 months, which is comfortably within the 24-month loan term.
The Amiral Constantin Bălescu area, also in Sector 1, is a well-established residential corridor with steady demand and typically faster liquidity than the luxury villa segment, complementing the collateral package with a more standard, more easily marketable residential unit.
Because the luxury segment carries elevated price volatility, the platform relies on the independent ANEVAR appraisal for Villa A and an evaluation for the apartment, rather than on asking prices or broker estimates. A forced-sale sensitivity of minus 20% on the combined collateral value of EUR 2,116,000 would imply a value of approximately EUR 1,693,000, which still covers the total loan facility of EUR 1,100,000 at a loan to value of approximately 65%.
6. Financial Analysis
This is working capital financing for a trading business, not a development project, so there is no projected sale price. The analysis focuses on the use of proceeds, the collateral coverage and the borrower's financial trajectory.
Use of proceeds
| Item | Amount | Share |
|---|---|---|
| Working capital to expand the trading business (inventory purchases and financing of an enlarged trade cycle to grow volumes) | EUR 682,752 | 100% |
| of which already subscribed in the four previous public offers | EUR 582,752 | 85.4% |
| of which new funding sought in this round | EUR 100,000 | 14.6% |
| Total | EUR 682,752 | 100% |
Maximum value of the offer: EUR 782,752 (up to EUR 200,000 of new funding); amounts subscribed above the funding target, up to the maximum, are accepted on the same terms.
The facility was pre-financed through a pre-financing round. The new funding raised in this round first repays the investors who pre-financed it, pro rata to the amount each pre-financed, so the total exposure of the borrower does not increase by the full amount of this round.
Collateral coverage
| Indicator | Value |
|---|---|
| Villa A (Caramfil), independent ANEVAR appraisal (02.06.2026) | EUR 1,716,000 |
| Apartment (Amiral Constantin Bălescu), evaluated | EUR 400,000 |
| Combined collateral value | EUR 2,116,000 |
| Mortgage registered in favour of stock.estate | EUR 1,650,000 |
| Total loan facility | EUR 1,100,000 |
| of which subscribed to date and sought in this campaign | EUR 682,752 (up to EUR 782,752 at the maximum) |
| Loan to value (on the total facility) | approx. 52% |
| Coverage ratio (on the total facility) | approx. 192% |
Company financials (statutory figures, RON)
| Indicator (RON) | 2023 | 2024 | 2025 |
|---|---|---|---|
| Net turnover | 9,563,150 | 49,855,609 | 31,433,111 |
| Net result | -1,746,337 | 1,136,887 | 1,653,916 |
| Total equity | 1,431,211 | 3,663,833 | 6,137,470 |
| Total debt | 13,215,231 | 15,371,386 | 7,811,355 |
2025 figures are the official year-end figures. Turnover reached approximately EUR 10.0 million in 2024 and approximately EUR 6.3 million in 2025, a normal amplitude for a commodity trading cycle. Equity has grown consistently, total debt has decreased and is predominantly commercial, and bank debt is minimal. The structural working capital need of the trading cycle is the economic rationale for the loan, and the proceeds are directed at growing trading volumes rather than at covering a deficit.
Cost of the facility. The borrower pays a fixed interest of 16% per annum on the amounts drawn. Investors receive between 10% and 16% per annum according to the amount invested, following the progressive rate bands displayed on this campaign page; the applicable band is shown before the investment is confirmed. The 4% one-off entry fee is borne by the borrower, not by investors.
Repayment source: operating cash flow from the trading activity, with bank refinancing available as a secondary route given the company's clean credit history, and realisation of the collateral as a final fallback (see Section 7).
7. Funding and Investment Opportunity
| Parameter | Terms |
|---|---|
| Total loan facility | EUR 1,100,000 |
| Funding target | EUR 682,752 |
| Already subscribed in the four previous public offers (pre-committed) | EUR 582,752 |
| New funding sought in this round | EUR 100,000 (funding target), up to EUR 200,000 (maximum) |
| Pre-financing | the facility was pre-financed through a pre-financing round; the new funding first repays the pre-financing investors, pro rata to the amount each pre-financed |
| Minimum target | EUR 582,752 (the pre-committed amount) |
| Maximum value of the offer | EUR 782,752; amounts subscribed above the funding target, up to the maximum, are accepted on the same terms |
| Campaign period | 01.10.2026 to 30.10.2026 |
| Loan term | 24 months |
| Maturity | 30.10.2028 |
| Interest rate to investors | progressive, 10% to 16% per annum, according to the amount invested (see rate bands on this page) |
| Interest rate after loan extension | 18% fixed per annum |
| Penalty interest rate | 20% fixed per annum |
| Day-count convention | 30/360 |
| Interest payment | monthly, at the end of each calendar month |
| Principal repayment | in full at maturity, 24 months after campaign close |
| Minimum investment ticket | EUR 100 |
| Entry fee | 4% one-off, borne by the borrower |
| Cashback | none |
| Security | first-rank mortgage over three residential units: Villa A (apartments A1 and A2, Caramfil) and one apartment (Amiral Constantin Bălescu), with land quotas and access shares |
| Mortgage status | already registered in favour of stock.estate for EUR 1,650,000 over both properties |
| Collateral coverage | combined value of EUR 2,116,000 (independent ANEVAR appraisal for Villa A; evaluation for the apartment); LTV approx. 52% and coverage approx. 192% on the total loan facility of EUR 1,100,000 |
| Disbursement mechanism | funds released exclusively at the notarial session |
Pre-financing. The project was pre-financed through a pre-financing round. The investors who pre-financed it will be repaid from this round, pro rata to the amount each of them pre-financed. Therefore the total exposure of the borrower does not increase by the full amount of this round: the new money raised first repays the pre-financing.
Platform. stock.estate is operated by STOCKESTATE CROWDFUNDING SRL, licensed under the European Crowdfunding Service Providers Regulation (ECSPR), Regulation (EU) 2020/1503, authorisation no. PJR28FSFPR/400002 (ASF Romania).
8. Risks and Mitigations
- Market risk (borrower). Turnover and profit vary from year to year in line with the ferroalloy price cycle, typical of trading activity. Mitigation: a 27-year track record across full commodity cycles, a lean cost base, growing equity, and a loan sized below the company's short-term financing need.
- Market risk (collateral). The luxury residential segment carries elevated price volatility. Mitigation: valuation is anchored to the independent ANEVAR appraisal for Villa A and an evaluation for the apartment; even a forced-sale haircut of 20% on the combined collateral leaves loan to value at approximately 65% on the total facility.
- Repayment risk. Principal is repaid in full at maturity rather than amortised. Mitigation: repayment is sourced from operating cash flow, with bank refinancing as a secondary route given the clean credit history, and realisation of the first-rank collateral (two properties) as a final fallback.
- Collateral liquidity risk. The villa has medium liquidity (estimated sale exposure time of 6 to 12 months), partially offset by the second, more standard apartment unit which typically carries faster liquidity. Mitigation: the villa's exposure time is comfortably within the 24-month loan term, and both assets sit in strong Sector 1 residential markets.
- Interest rate variability across investors. Under the progressive model, the rate each investor receives depends on the amount invested, so smaller tickets earn a lower rate than larger ones. Mitigation: the applicable rate band is shown on this page before the investment is confirmed, and every investor ranks equally under the same first-rank mortgage regardless of the rate band.
- Regulatory and structuring risk. The security depends on correct registration of the mortgage. Mitigation: the first-rank mortgage over both properties, totalling EUR 1,650,000, is already registered in the land book in favour of stock.estate, and funds are released exclusively at the notarial session.
- Funding-completion risk. The public campaign must reach its target within the campaign deadline. Mitigation: EUR 582,752 is already subscribed and the loan is fully secured from day one by the registered first-rank mortgage over both properties.