Sea View Costinesti
- Type of property
- Residential
- Location
- Costinesti, Constanta County, Romania
- Loan duration
- 12 months
- Interest rate
- 10-16% / yearProgressive Interest
- Payment
- Monthly
- Time left
- 16 days
- Funding target
- € 1 171 500
- Precommitted amount
- € 671 500
- Loan to value
- 38.05 %
- Collateral
- Real estate mortgage
2 investors invested € 671 500
€ 671 500
€ 921 500
57.32% funded
€ 1 171 500
1. Executive Summary
GUARDA TACOZ S.R.L. and NIVIMI RED CONSTRUCT S.R.L., two Romanian companies that jointly own in equal shares a 3,163 sqm plot in the northern development area of Costinesti on the Romanian Black Sea coast, are opening their first offer on stock.estate. The facility is up to EUR 500,000 over 12 months. The two companies are joint and several co-borrowers: each is liable for the whole. They have already deployed EUR 671,500 of their own equity into the project, shown as committed in the offer structure.
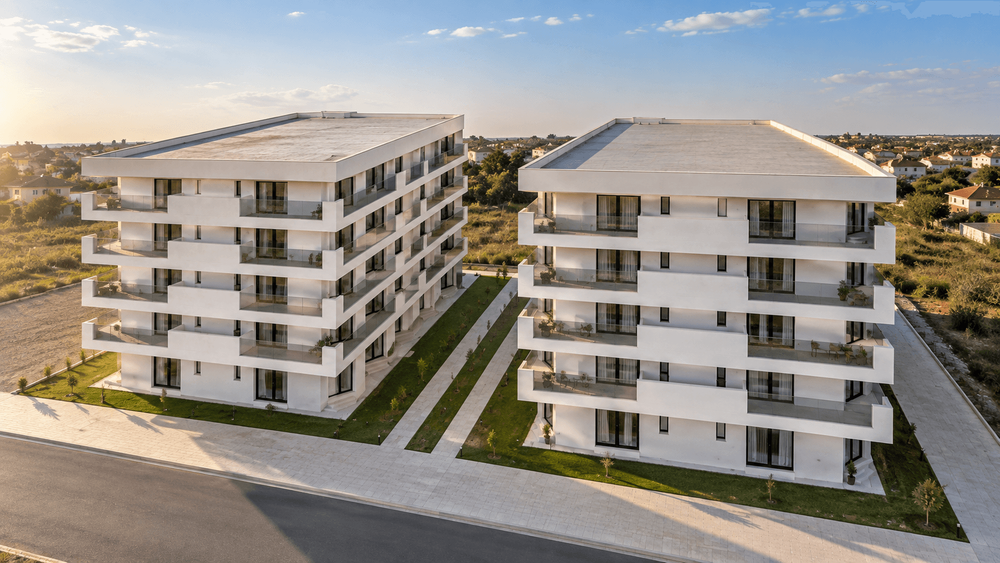
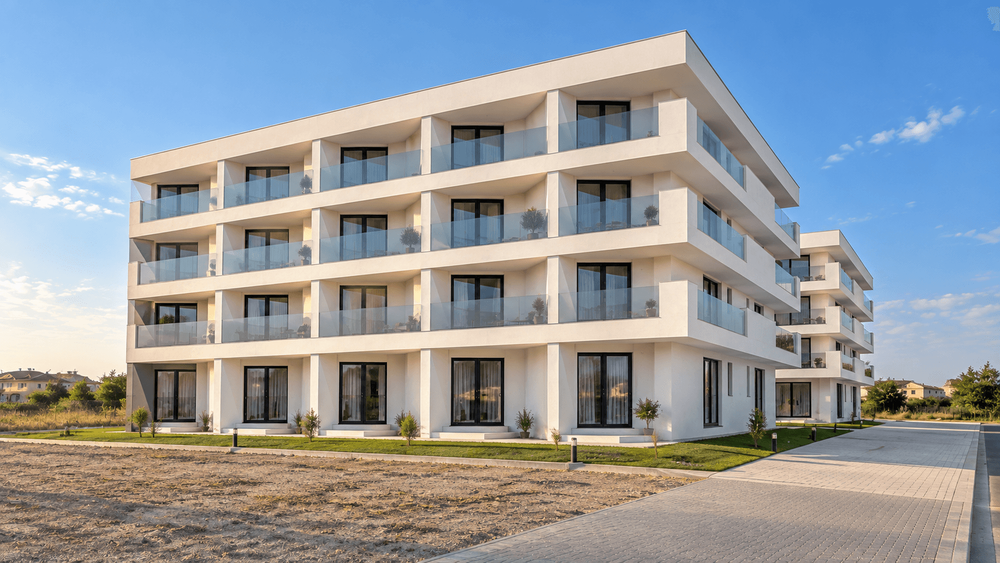
Building permit no. 50 of 12 May 2026 authorises two P+4E buildings on the plot, 140 apartments in total. The Project Developers are building them in sequence and funding the project in tranches. This offer is the first tranche and funds block C1, the building now under construction: 50 apartments, 2,600.07 sqm of gross built area and 2,057.60 sqm of usable apartment area. Part of the proceeds also pays the outstanding balance of the land purchase price. Block C2, the larger building of 90 apartments, is to be built in a later phase and is not financed by this offer.
Investors receive a progressive interest rate between 10.00% and 16.00% per annum, fixed at the moment each investment is signed according to the invested amount, within an interest pool of 6.00 percentage points above the 10.00% floor rate. Interest is paid monthly and the principal is repaid in a single instalment at maturity. No cashback and no investor-facing fees apply.
The loan is secured by a first-rank mortgage over the whole property and over all present and future constructions on it: the land registered under CF 115676 Costinesti and both buildings, C1 under CF 115676-C1V and C2 under CF 115676-C2V. An ANEVAR member values the land at EUR 996,000 and the works already standing on it at EUR 318,000, a collateral value of EUR 1,314,000. Against the EUR 500,000 facility this is a loan-to-value ratio of 38.05% and collateral coverage of 263%, against a platform minimum of 150%. The mortgage is registered at the notarial session at which the funds are released, so there is no window in which investor capital is unsecured.
2. Location Analysis
The property is located in the village of Costinesti, Costinesti commune, Constanta County, on the Romanian Black Sea coast, in the "Zona Nord" area governed by the detailed urban plan approved by local council decision no. 63 of 16 December 2010. The plot fronts str. Portului.
Costinesti is one of the established resorts on the southern Romanian littoral, positioned between Constanta to the north and Mangalia to the south, both within roughly half an hour by road. The resort's economy is seasonal and tourism-driven, with a resident population well below its summer occupancy. Demand for apartments in the resort comes from two sources: buyers acquiring a holiday unit for personal use, and buyers acquiring small units for short-term rental during the season.
Constanta County is one of the more active residential markets in Romania. The county recorded 18,978 property transactions between January and August 2025, up 6.3% year on year, and 2,670 transactions in April 2026, up 16% on April 2025. The average price per usable square metre in Constanta reached EUR 1,822 in 2024, a 12% increase on 2023, against EUR 1,593 in 2021 and EUR 904 in 2014.
The independent appraisal identifies land offers in the Costinesti Zona Nord micro-location at EUR 350.00, EUR 354.55 and EUR 379.41 per sqm, all asking prices with a negotiation margin of around 10%, and notes that the supply of comparable building plots in the area is limited.
3. Developer Profile
The project is developed by two companies acting jointly. Both have CAEN 4100, construction of residential and non-residential buildings, as their declared main activity, and both hold the land and the buildings in equal 50/100 shares. The building permit was issued to both, GUARDA TACOZ S.R.L. and SOLID HOUSE STEEL S.R.L., the latter being the former name of NIVIMI RED CONSTRUCT S.R.L.
GUARDA TACOZ S.R.L.
- Romanian limited liability company, registered 19 April 2021, registration number J2021001301138 (formerly J13/1301/2021), tax code 44136579
- Registered office: Municipiul Constanta, Aleea Siracuzza nr. 1, Statiunea Mamaia, Lot 2, Vila Turistica C2, camera 1, etaj 3, ap. 18, Constanta County
- Sole shareholder: Borgognon Iulian-Dumitru, 100%; administrator: Brinzariu Constantin, since 16 April 2021
- Subscribed and paid-up capital: RON 200
- Status per company registry certificate no. 3351044 of 9 September 2026: active, with no insolvency, dissolution or opposition recorded
- Activity: development and sale of residential and holiday property in Constanta County. Net turnover of RON 6,502,488 and net profit of RON 2,403,561 in 2024; net turnover of RON 1,876,298 and net loss of RON 551,722 in 2025 as activity shifted to the acquisition and development of the Costinesti site
NIVIMI RED CONSTRUCT S.R.L. (formerly SOLID HOUSE STEEL S.R.L.)
- Romanian limited liability company, registered 9 August 2017, registration number J2017002846138 (formerly J13/2846/2017), tax code 38085071
- Registered office: sat Costinesti, comuna Costinesti, str. Emil Costinescu nr. 36, Constanta County
- Sole shareholder and administrator: Rosu Cristian, 100%, mandate renewed 30 July 2026
- Subscribed and paid-up capital: RON 200
- Status per company registry certificate no. 3364594 of 10 September 2026: active, with no insolvency, dissolution or opposition recorded
- Activity: construction. No turnover recorded in 2023, 2024 or 2025, and a net loss of RON 54,901 in 2025, the company's resources having been directed to the acquisition of the Costinesti site
Both companies are small vehicles rather than trading businesses: GUARDA TACOZ reported one employee in each of the last three years and NIVIMI RED CONSTRUCT reported none in 2024 and 2025. Repayment of this loan does not depend on their current operating revenue; it depends on the project and on the collateral.
4. Project Overview
The permit covers two P+4E buildings on one plot. Block C1 is under construction and is the building financed by this offer. Block C2 follows in a later phase. The mortgage securing the loan covers the whole property: the plot and everything erected on it, present and future, so it extends to both buildings.
Land
- Address: str. Portului, sat Costinesti, comuna Costinesti, Constanta County, Romania
- Land book: CF 115676 Costinesti, cadastral number 115676, intravilan land, 3,163 sqm, Lot 7 + Lot 12, Lot 13, Cvartal 9, residential and holiday-housing designation under the "Zona Nord" detailed urban plan
- Created by merging CF 100023 and CF 110970 under notarial deed no. 86 of 2 February 2026 and administrative act no. 12 of 19 January 2026
- Ownership: GUARDA TACOZ S.R.L. 50/100 and NIVIMI RED CONSTRUCT S.R.L. 50/100, per land register extract no. 39314 of 7 September 2026
Block C1, the financed building
- Land book: CF 115676-C1V, cadastral number 115676-C1V, registered provisionally as a future asset, 1/2 share each, under building permit no. 50 of 12 May 2026 and notarial deed no. 951 of 13 May 2026
- Configuration: ground floor plus four upper floors (P+4E)
- 50 apartments, ten per level
- Footprint: 449.23 sqm at ground level
- Gross built area: 2,600.07 sqm
- Usable apartment area including balconies: 2,057.60 sqm, an average of roughly 41 sqm per apartment
Block C2, a later phase
- Land book: CF 115676-C2V, cadastral number 115676-C2V, registered provisionally as a future asset, 1/2 share each, under the same building permit and notarial deed
- Configuration: ground floor plus four upper floors (P+4E), 90 apartments
- Footprint: 814.43 sqm at ground level; gross built area 4,623.84 sqm; usable apartment area including balconies 3,728.00 sqm
- Not financed by this offer. It falls under the same first-rank mortgage and adds to the security as it is built
Permits and approvals
- Building permit no. 50 of 12 May 2026, issued by Costinesti Town Hall to both companies, for two P+4E buildings. Built area 1,263.656 sqm, gross built area 7,223.848 sqm, usable area 6,179.499 sqm. Urban planning certificate no. 28 of 11 February 2026: site coverage ratio below the 40% maximum, floor area ratio proposed 1.99 against a maximum of 2
- General designer: Geabana V. Luiza-Marina, Individual Architecture Office, project no. 02/2026
- Technical verification reports no. 746 of 7 May 2026 (fields B1, D1, E, F) and no. 1350 of 6 May 2026 (field A1, structural resistance)
- Environmental screening decision ANMAP no. 103 of 6 April 2026; Constanta County Directorate for Culture opinion no. 938 of 12 March 2026; siting opinion from Retele Electrice Romania
- Start of works notified to the town hall on 27 May 2026, works started 28 May 2026. The 24-month execution term therefore runs to approximately 28 May 2028
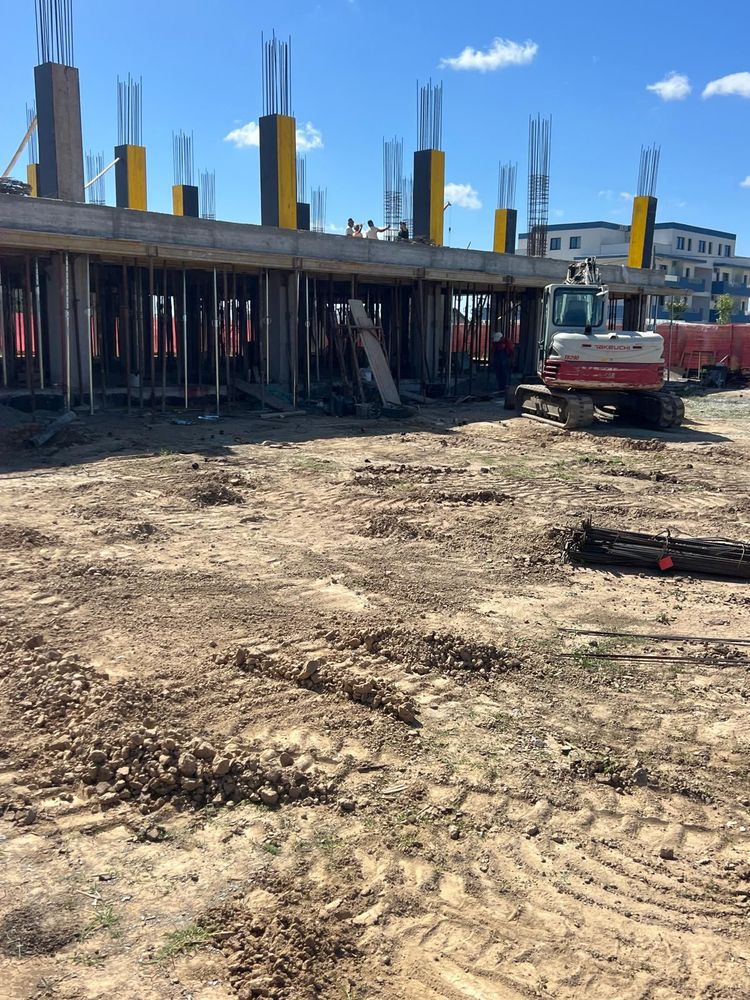
Construction status at 10 September 2026
- Excavation complete
- Slab over the ground floor cast
- First-floor columns reinforced, formwork and props in place
- Excavator on site
- Valued by the independent appraiser at the inspection of 4 September 2026, on a segregated cost of EUR 1,027 per gross built square metre, the works standing on the site amount to EUR 317,892
Archaeology. The site lies within the Costinesti-Parthenopolis archaeological site, national archaeological repertory code 607749.01. The county culture directorate's opinion requires an archaeological research report and adaptation of the project if remains are found.
5. Market Analysis
The independent appraisal, report no. 562 of 11 September 2026 prepared by Sasu Nicolae, full member of ANEVAR (licence no. 19020, specialisations EPI and EBM) following an inspection on 4 September 2026, establishes the following parameters for the Costinesti micro-location.
| Parameter | Value | Source |
|---|---|---|
| Asking prices, comparable residential units | EUR 1,200 to EUR 1,800 per sqm | ANEVAR report no. 562, supply analysis |
| Asking prices, comparable building plots, Zona Nord | EUR 350.00, EUR 354.55 and EUR 379.41 per sqm | ANEVAR report no. 562, land comparables |
| Negotiation margin on mature offers | 3% to 5% | ANEVAR report no. 562 |
| Land value applied in the valuation | EUR 315 per sqm | ANEVAR report no. 562, direct comparison |
| Construction cost applied in the valuation | EUR 1,027 per gross built sqm | ANEVAR report no. 562, segregated cost method |
| Average price, Constanta county seat, 2024 | EUR 1,822 per usable sqm, +12% on 2023 | Constanta market data |
The appraiser describes the sale market as characterised by moderate supply with no sign of increase, and solvent purchase demand that is growing, supported by the evolution of lending. Rental demand for this property type is assessed as low and stagnant.
Pricing rationale. The Project Developers' target sale price is EUR 1,300 per usable square metre. That price sits in the lower part of the appraiser's observed range of EUR 1,200 to EUR 1,800 per sqm for comparable units in the micro-location, and at 71% of the 2024 average for the Constanta county seat. Block C1 is concentrated in small units, averaging roughly 41 sqm of usable area, which in the Romanian coastal market trade at a higher price per square metre than larger units because the absolute ticket is lower and the product is suited to seasonal rental. The pricing assumption is therefore conservative relative to the documented range rather than above it. Investors should note that the price is quoted net of VAT, that the achieved price is not contractually fixed, and that the absorption of 50 units in block C1, and of 140 across the project, in a seasonal resort market may take longer than a single selling season.
6. Financial Analysis
This is a development transaction: the land is already acquired, construction is under way on block C1, and the exit is the sale of the finished apartments. The Project Developers build at an all-in contracted cost of EUR 800 per gross built square metre, land included, stated net of VAT, and target a sale price of EUR 1,300 per usable square metre plus VAT. Areas are taken from the architectural documentation approved under building permit no. 50 of 12 May 2026.
The economics are shown for the project as a whole, both buildings and 140 apartments, because the land, the permit, the design and the mortgage all cover the two buildings together. This offer finances the first tranche, block C1.
Use of proceeds
| Item | Amount (EUR) | Share |
|---|---|---|
| Origination fee, 4.00%, retained at drawdown | 20,000 | 4.0% |
| Balance of the land purchase price to R V A Consulting Company S.R.L. | 239,190 | 47.8% |
| Construction works on block C1 and working capital | 240,810 | 48.2% |
| Total facility | 500,000 | 100% |
Net proceeds available to the borrowers at drawdown are EUR 480,000, of which EUR 239,190 is applied directly at the notarial session to discharge the seller's legal mortgage.
Developer equity already deployed
| Item | Amount (EUR) |
|---|---|
| Land consideration paid: EUR 45,560 to R V A Consulting Company S.R.L. and RON 1,618,015.80 to Costinesti Sea View Construct S.R.L. | 353,543 |
| Works executed on block C1, recognised by the independent appraiser at 4 September 2026 | 317,892 |
| Total equity deployed | 671,435 |
That is 11.4% of the total project cost, committed before any investor capital is drawn.
Project economics, both buildings
| Item | Amount (EUR) |
|---|---|
| Gross built area authorised, blocks C1 and C2 | 7,223.91 sqm |
| Usable apartment area for sale, 140 apartments | 5,785.61 sqm |
| All-in development cost at EUR 800 per gross built sqm, land included | 5,779,126 |
| of which already deployed at 4 September 2026 | 671,435 |
| Cost to complete | 5,107,691 |
| Estimated cost of external financing on this tranche, 12 months | 100,000 |
| Total project cost | 5,879,126 |
| Aggregate sale value, 5,785.61 usable sqm at EUR 1,300 per sqm, excluding VAT | 7,521,288 |
| Gross margin before financing | 1,742,162 |
| Net result after financing | 1,642,162 |
| Margin on revenue | 21.8% |
| Margin on cost | 27.9% |
| Margin per usable sqm | EUR 284 |
| Break-even sale price per usable sqm | EUR 1,016 |
The two buildings side by side
| Item | Block C1, financed | Block C2, later phase | Both |
|---|---|---|---|
| Apartments | 50 | 90 | 140 |
| Gross built area, sqm | 2,600.07 | 4,623.84 | 7,223.91 |
| Usable apartment area, sqm | 2,057.60 | 3,728.00 | 5,785.61 |
| All-in cost at EUR 800 per gross built sqm | 2,080,053 | 3,699,074 | 5,779,126 |
| Sale value at EUR 1,300 per usable sqm | 2,674,884 | 4,846,404 | 7,521,288 |
| Gross margin | 594,831 | 1,147,330 | 1,742,162 |
| Gross margin on revenue | 22.2% | 23.7% | 23.2% |
| Break-even per usable sqm | EUR 1,011 | EUR 992 | EUR 999 |
Why the gap between EUR 800 and EUR 1,300 is not a 38% margin. The two figures are measured on different areas. The cost applies to gross built area, which includes stairwells, corridors, lift shafts, structure and technical space. The price applies only to the usable apartment area that is actually sold, which is 80.1% of gross built area across the two buildings. Revenue per gross built square metre is therefore EUR 1,041, not EUR 1,300, against an all-in cost of EUR 800. That is where the 23.2% gross margin comes from.
Sensitivity. Each EUR 100 per usable square metre moves the result by approximately EUR 579,000 across the project.
| Achieved price per usable sqm | Net result after financing (EUR) | Margin on revenue |
|---|---|---|
| 1,016 | 0 | 0.0% |
| 1,100 | 485,040 | 7.6% |
| 1,200 | 1,063,601 | 15.3% |
| 1,300, the target | 1,642,162 | 21.8% |
| 1,400 | 2,220,722 | 27.4% |
The break-even price of EUR 1,016 per usable square metre sits 15% below the bottom of the EUR 1,200 to EUR 1,800 band of asking prices the independent appraiser observed for comparable units in the micro-location.
Borrower financials, as filed with ANAF (RON)
| Indicator | GUARDA TACOZ 2023 | 2024 | 2025 | NIVIMI 2023 | 2024 | 2025 |
|---|---|---|---|---|---|---|
| Fixed assets | 811,706 | 219,019 | 115,616 | 1,250 | 0 | 0 |
| Current assets | 4,122,629 | 5,819,205 | 4,113,249 | 1,047,705 | 529,601 | 353,235 |
| of which inventories | 3,287,864 | 2,018,060 | 44,475 | 0 | 0 | 88 |
| of which receivables | 382,669 | 3,627,079 | 3,869,268 | 1,043,143 | 346,463 | 351,200 |
| of which cash and bank | 452,096 | 174,066 | 199,506 | 4,562 | 183,138 | 1,947 |
| Total debt | 4,923,298 | 3,624,858 | 2,838,445 | 18,806 | 24,713 | 33,906 |
| Total equity | 11,037 | 2,414,597 | 1,390,420 | 1,030,149 | 504,888 | 319,329 |
| Net turnover | 0 | 6,502,488 | 1,876,298 | 0 | 0 | 0 |
| Total income | 1,969,726 | 9,512,391 | 2,047,030 | 593 | 2,130 | 0 |
| Total expenses | 1,904,944 | 7,108,830 | 2,598,752 | -34,956 | 36,205 | 54,901 |
| Net result | +64,782 | +2,403,561 | -551,722 | +30,426 | -34,075 | -54,901 |
| Average employees | 1 | 1 | 1 | 1 | 0 | 0 |
The reference exchange rate used elsewhere in this page is RON 5.2536 per EUR, as applied in the valuation report.
Repayment source
The principal is repaid in a single instalment at the end of month 12, on 30 September 2027. Repayment comes from the sale of the apartments in block C1, if construction advances quickly enough for units to be delivered and sold within the term, and otherwise from bank refinancing secured on the same property. Additional shareholder capital and a follow-on stock.estate facility are further channels available to the Project Developers.
7. Funding and Investment Opportunity
| Parameter | Value |
|---|---|
| Facility in this offer | EUR 500,000 |
| Developer equity already deployed, shown as committed | EUR 671,500 |
| Total value of the offer displayed on the platform | EUR 1,171,500 |
| Minimum funding target | EUR 250,000 of new funding |
| Building financed by this offer | Block C1, CF 115676-C1V, 50 apartments |
| Loan term | 12 months from the close of the campaign on 30 September 2026, maturity 30 September 2027 |
| Remuneration interest rate to investors | Progressive, from 10.00% to 16.00% per annum, fixed at signing according to the invested amount |
| Floor rate and interest pool | 10.00% floor rate plus an interest pool of 6.00 percentage points |
| Interest rate paid by the borrowers | 16.00% per annum |
| Interest rate after loan extension | 18.00% per annum, fixed |
| Penalty interest rate | 20.00% per annum, fixed |
| Cashback | None |
| Investor fees | None |
| Interest payment frequency | Monthly, at the end of each calendar month |
| Principal repayment | Single instalment at maturity |
| Day-count convention | 30/360 |
| Minimum investment ticket | EUR 100 |
| Borrowers | GUARDA TACOZ S.R.L. and NIVIMI RED CONSTRUCT S.R.L., joint and several |
| Security instrument | First-rank mortgage over the land (CF 115676) and over all present and future constructions on it, blocks C1 (CF 115676-C1V) and C2 (CF 115676-C2V) |
| Collateral basis | Independent commercial appraisal, ANEVAR, report no. 562 of 11 September 2026 |
| Underlying valuation | EUR 1,314,000, of which land EUR 996,000 and works standing on the land EUR 318,000 |
| Effective collateral coverage | 263% |
| Loan-to-value | 38.05% |
| Mortgage timing | Registered at the notarial session at which the funds are released |
| Disbursement mechanism | Single drawdown at the notarial closing, simultaneous with payment of the balance of the land price and discharge of the seller's legal mortgage |
How the progressive rate works
Each investment receives its own annual contract rate, fixed at the moment it is signed. The rate starts at the 10.00% floor and rises within the 6.00 percentage point interest pool according to the amount invested, following the rate bands published on this campaign page. The borrowers pay 16.00% per annum on the whole facility; the part of the pool not allocated to investors is the platform's fee. Once signed, the rate of an investment does not change for the life of the loan.
Security mechanics
At the date of this page the property carries one registered charge: a legal mortgage of EUR 284,750 in favour of R V A Consulting Company S.R.L., the seller of a 36/100 share of the land, securing the unpaid balance of that purchase price. It is the only charge on the title.
At the notarial closing, in a single session: the balance of EUR 239,190 is paid to R V A Consulting Company S.R.L. from the proceeds of this offer; the seller's legal mortgage is discharged; and the first-rank mortgage in favour of the investors is registered over the land and over all present and future constructions on it. Funds are released only at that session. There is no period in which investor capital is unsecured and no period in which the investors' mortgage ranks behind another charge.
Capital stack and funding plan
| Layer | Amount (EUR) |
|---|---|
| Total project cost, both buildings, all-in at EUR 800 per gross built sqm | 5,879,126 |
| Developer equity already deployed | 671,435 |
| stock.estate facility, this offer | 500,000 |
| Cost still to be funded | 4,707,691 |
Of the cost still to be funded, approximately EUR 1.63 million relates to block C1, the building this offer finances, and the balance to block C2. The cost to complete is not covered by this offer. The Project Developers state that it will be funded from their own resources, from pre-sales of the apartments, and from further financing arranged separately, including later tranches.
Named repayment channels for the principal, in order of preference:
- Proceeds from the sale of the apartments in block C1, including pre-sales concluded before completion
- Bank refinancing secured on the same property
- Additional shareholder capital
- A follow-on stock.estate facility, subject to the collateral coverage requirement in force at the time
Platform
stock.estate is a European Crowdfunding Service Provider licensed by the Autoritatea de Supraveghere Financiara of Romania under licence PJR28FSFPR/400002, operating under Regulation (EU) 2020/1503 (ECSPR).
8. Risks and Mitigations
-
Completion risk. The cost to complete the project is EUR 5,107,691, of which approximately EUR 1.63 million relates to block C1. That is many times the size of this facility and is not funded by it. If the Project Developers cannot raise it, the buildings may remain unfinished. Mitigation: the loan is secured on the current market value of the land and the works standing on it rather than on a completed building, at a loan-to-value of 38.05%; the land alone is appraised at EUR 996,000, twice the facility.
-
Construction cost risk. The economics on this page rest on the Project Developers' own all-in contracted cost of EUR 800 per gross built square metre, land included, as declared by them. Material prices and subcontractor availability on the Romanian coast can move over a two-year build. Mitigation: NIVIMI RED CONSTRUCT executes the works with its own crew at a cost it has contracted, the loan is secured on the property rather than on the project margin, and the developers carry the cost risk themselves.
-
Staged financing. The project is designed to be funded in tranches and this offer is the first. Later tranches are not committed, are not underwritten by stock.estate today and depend on market conditions and on the collateral coverage requirement in force at the time. Mitigation: this offer is sized and secured on its own, independently of whether later tranches happen.
-
Repayment timing. The loan matures on 30 September 2027 while the execution term under the building permit runs to approximately 28 May 2028. Delivery and sale of the apartments within the term of the loan depends on construction advancing faster than the permitted schedule. Mitigation: bank refinancing secured on the same property is the alternative channel, and the loan-to-value of 38.05% leaves headroom for it; additional shareholder capital and a follow-on platform facility are further options.
-
Absorption risk. The Romanian coastal residential market is strongly seasonal. Absorption of 50 units in block C1, and of 140 across the project, may take longer than a single selling season and the achieved price is not contractually fixed. Mitigation: the target price of EUR 1,300 per usable square metre sits in the lower part of the observed range, and the units average roughly 41 sqm, a format that is liquid both for holiday buyers and for seasonal rental investors.
-
Archaeological risk. The site sits within the Costinesti-Parthenopolis archaeological site, code 607749.01. The county culture directorate requires an archaeological research report and adaptation of the project if remains are found, which could delay works. Mitigation: the culture directorate issued a favourable opinion, no. 938 of 12 March 2026, and excavation on the site is already complete.
-
Borrower financial capacity. Both companies are small vehicles with no operating revenue attributable to this project: GUARDA TACOZ reported a net loss of RON 551,722 in 2025 and NIVIMI RED CONSTRUCT reported no turnover and a net loss of RON 54,901. Mitigation: the two are joint and several co-borrowers, each liable for the whole; both are recorded as active with no insolvency, dissolution or opposition in company registry certificates dated 9 and 10 September 2026; and repayment is secured on the property rather than on earnings.
-
Enforcement risk. Both buildings are registered in the land book provisionally, as future assets, and their definitive registration depends on completion of the works. Enforcement over a partially built structure takes time and a forced sale may realise materially less than the appraised market value. Mitigation: the mortgage covers the freehold land as well as everything built on it, and the land is separately appraised at EUR 996,000, which alone is 199% of the facility.
-
Currency risk. The loan is denominated in euro while the borrowers' costs are predominantly in Romanian lei. A depreciation of the leu increases the local-currency cost of servicing and repaying the facility. Mitigation: apartment prices on the Romanian coast are commonly quoted and negotiated in euro, providing a partial natural offset.
-
Variable rate at signing. The contract rate of each investment depends on the amount invested and on the conditions in force at signing, so two investors in the same campaign may receive different rates. Mitigation: the rate is displayed before signing, is fixed for the life of the loan once signed, and can never fall below the 10.00% floor.
-
Illiquidity. Loans concluded through the platform are not admitted to trading on a regulated market and no secondary market is guaranteed. Investors should be prepared to hold the investment to maturity.
The project owner declares that, to the best of their knowledge, no information has been omitted or is materially misleading or inaccurate. The project owner is responsible for the preparation of the key investment information sheet (see Documents).












All investments involve risks, including loss of invested capital, lack of liquidity, and non-reimbursement on loans, partially or integrally. It is an appropriate investment only for investors able to assess and bear the risks presented above. Before investing, please read the risks of investments warning, and also all the clauses of the loan agreement, which will be provided to you for the campaign in question. Stock.estate Platform is not responsible for the information provided by the project developers, even if it is provided by or through Stock.estate. Stock.estate does not provide you any other advisory services. The decision to invest is entirely yours. We recommend that you consult specialized advisers if you need support in evaluating your investment decision. The messages and documentation you receive from Stock.estate or project developers have not been verified or approved by Romanian or European authorities.