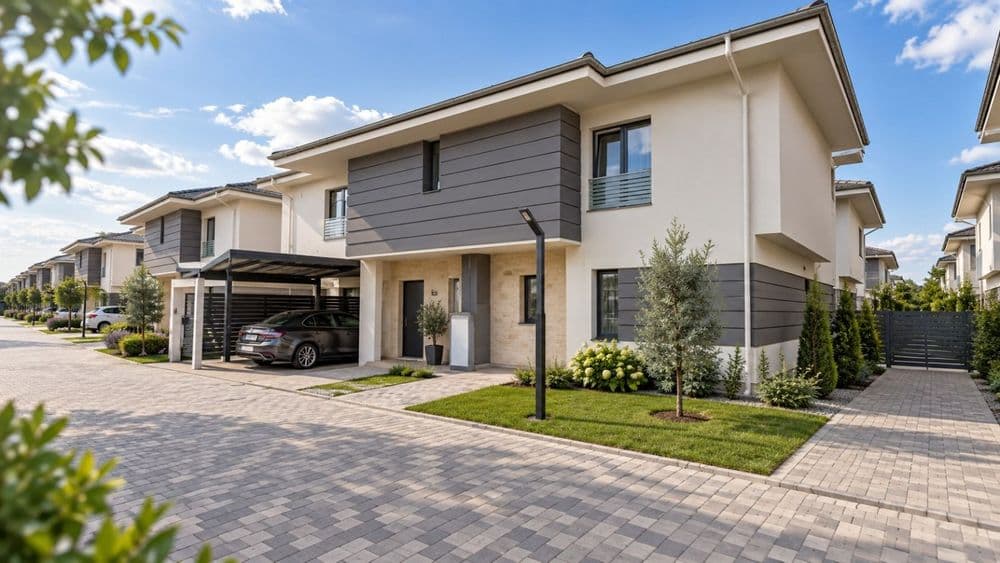
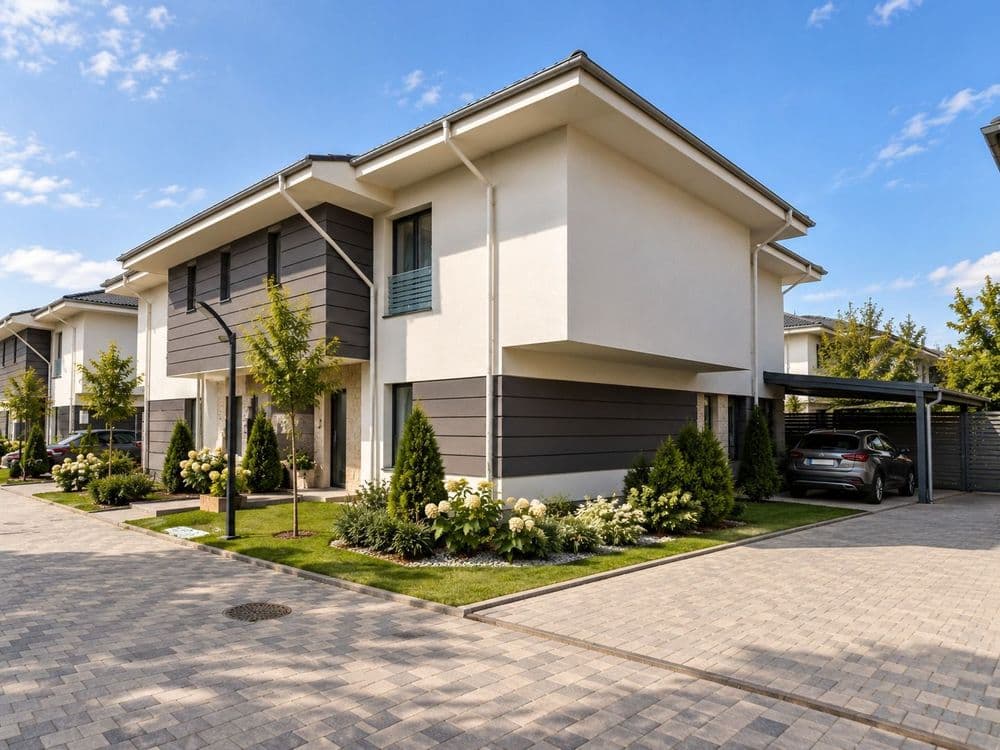
Grivita nr. 42-14
- Type of property
- Residential
- Location Open in Gmaps 🗺️
- Otopeni, Ilfov County, Romania
- Loan duration
- 6 months
- Interest rate
- 10-16% / year
- Payment
- Monthly
- Time left
- 1 day
- Funding target
- € 550 000
- Precommitted amount
- € 275 000
- Loan to value
- 65.68 %
- Collateral
- Real estate mortgage
116 investors invested € 413 741.53
€ 275 000
€ 275 000
75.23% funded
€ 550 000
Reimbursement progress: 0%
1. Executive Summary
SELEX TRADING S.A., a Romanian joint-stock company active since 2010 in the letting of its own real estate (CAEN 6820), is raising a EUR 275,000 working capital loan over 6 months through the stock.estate platform. This is the company's first offer on the platform.
Investors receive a progressive interest rate between 10.00% and 16.00% per annum, fixed at the moment each investment is signed according to the invested amount, within an interest pool of 6.00 percentage points above the 10.00% floor rate. Interest is paid monthly and the principal is repaid in a single instalment at maturity. No cashback and no investor-facing fees apply.
The loan is secured by first-rank mortgages over three properties owned by the borrower: a house under completion with its plot of 230 sqm at str. Grivitei nr. 42-14, Otopeni, Ilfov County (CF 117529), the adjoining vacant plot of 247 sqm (CF 121186), and a 6,866 sqm intravilan plot with its outbuildings at Calea Bucuresti nr. 19, Murfatlar, Constanta County (CF 100017). ANEVAR members value the Otopeni properties at EUR 238,100 (report no. 56 of 16 June 2025) and the Murfatlar property at EUR 180,600 (report of 13 March 2026), a combined collateral value of EUR 418,700. Against the EUR 275,000 facility this is a loan-to-value ratio of 65.68% and collateral coverage of 152%, against a platform minimum of 150%. The mortgages are registered at the notarial session at which the funds are released, so there is no window in which investor capital is unsecured.
2. Location Analysis
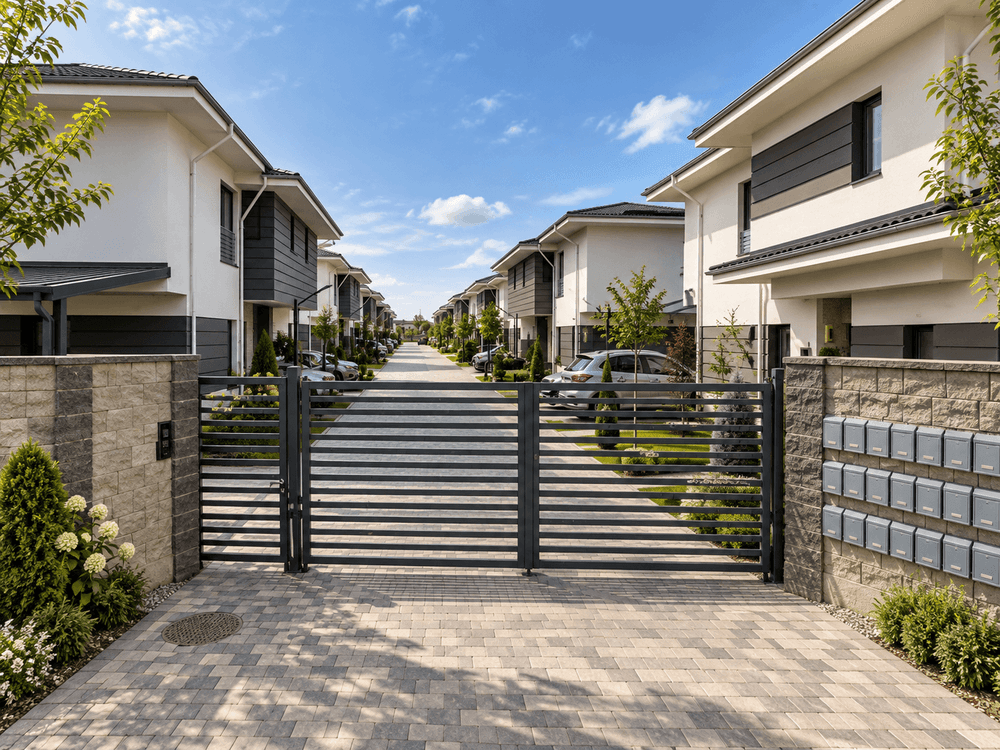
Otopeni, Ilfov County. The two Otopeni properties are located on str. Grivitei, in the central area of Otopeni, a town of the Bucharest metropolitan area immediately north of the capital and home to Henri Coanda International Airport. The independent appraiser describes the micro-location as the town's new single-family housing zone, with very low traffic, all utilities connected (electricity, gas, water, sewerage), public transport on the national road, and the town hall, a World Class fitness club and several supermarkets in the immediate vicinity. Otopeni is one of the most sought-after residential locations in the Bucharest suburbs, supported by proximity to the airport, the Baneasa and Pipera business districts and the DN1 corridor.
Murfatlar, Constanta County. The third property is located at Calea Bucuresti nr. 19, in the median area of Murfatlar, a town about 15 km west of Constanta on the road corridor towards Bucharest. The appraiser characterises the zone as predominantly industrial-residential, with access from an asphalted public road and electricity, water and sewerage networks available. The plot was acquired in 2023 from a wine-producing company and carries a set of outbuildings dating from around 1970, most of which the appraiser rates as demolishable.
3. Borrower Profile
The borrower is SELEX TRADING S.A. (tax code RO26771432, trade register number J2022023750401, EUID ROONRC.J2022023750401), a joint-stock company registered on 13 April 2010 in Iasi County (formerly J22/526/2010) and re-registered in Bucharest on 28 November 2022. Its registered office is at str. Banul Antonache nr. 40-44, office MRSF20, 1st floor, Sector 1, Bucharest, and its declared main activity is CAEN 6820, renting and operating of own or leased real estate. Subscribed and paid-up capital is RON 90,000.
- Shareholders: Ciausu Angelica, 94.44%; CASA RANDUNICA S.R.L. (tax code 43365302, Iasi County), 5.56%. Ciausu Angelica also holds 100% of CASA RANDUNICA S.R.L. and is therefore the ultimate beneficial owner of 100% of the borrower.
- Sole administrator: Ciausu Angelica, mandate 22 March 2022 to 22 March 2042.
- Status per company registry certificate no. 3563776 of 23 September 2026: in operation, with no insolvency, dissolution or opposition recorded. Criminal record certificate of the administrator dated 23 September 2026 is on file.
- Activity and assets: the company holds a portfolio of real estate in Constanta County (Murfatlar) and Ilfov County (Otopeni), two registered secondary establishments in Murfatlar, and a portfolio of registered trademarks. It has 100% participations in LIVADA URSULUI S.R.L. (Bistrita-Nasaud County) and AGRO TEAM FRUCT S.R.L. (Medgidia, Constanta County).
- Scale: the company had an average of 2 employees in 2025. Its business is asset holding and letting rather than trading, which is reflected in the balance sheet structure described in section 6.
4. Collateral Overview
The security comprises three properties, all registered in the sole ownership (1/1) of SELEX TRADING S.A.
Property 1: house under completion and plot, Otopeni
- Address: str. Grivitei nr. 42-14, T12, P253/2, corp 4B, Otopeni, Ilfov County
- Land book: CF 117529 Otopeni, cadastral number 117529; intravilan plot of 230 sqm, courtyard and buildings category, rectangular, flat, approximately 12 m frontage to a right-of-way road off str. Grivitei
- Building: C1, cadastral number 117529-C1, single-family house P+1E, footprint 67 sqm, gross built area 145 sqm, usable area 112.97 sqm, registered in the land book in 2021; reinforced concrete frame and brick masonry, two-slope Lindab sheet roof, 10 cm thermal insulation, PVC double-glazed windows, electricity, gas, water and sewerage installations executed
- Stage: at the appraiser's inspection of 5 June 2025 the house was approximately 75% complete, without interior finishes, which are to be executed to the standard of the finished twin house on the neighbouring plot
- Title: acquired by notarial sale-purchase deed of 24 February 2025 from a private individual; land register extract of 6 May 2025 shows no charges
- Valuation: EUR 197,100 (RON 991,200), EUR 1,744.71 per usable sqm, by Nicoleta Ungureanu, ANEVAR member no. 18021, report no. 56 of 16 June 2025, market comparison approach
Property 2: vacant plot, Otopeni
- Address: T12, P253/1, Lot 7, Otopeni, Ilfov County, adjoining Property 1
- Land book: CF 121186 Otopeni, cadastral number 121186; intravilan plot of 247 sqm
- Title: sole ownership of SELEX TRADING S.A.; land register extract of 6 May 2025 shows no charges
- Valuation: EUR 41,000 (RON 206,000), EUR 165.17 per sqm, same report no. 56 of 16 June 2025
Both Otopeni properties are served by a private access road registered under CF 114989 Otopeni (546 sqm), in which SELEX TRADING S.A. holds a 1/13 undivided share. The charge previously registered on that share in favour of a non-bank lender has been discharged.
Property 3: land and outbuildings, Murfatlar
- Address: Calea Bucuresti nr. 19, Murfatlar, Constanta County
- Land book: CF 100017 Murfatlar, cadastral number 100017; intravilan plot of 6,866 sqm, courtyard and buildings category, access from an asphalted public road, electricity, water and sewerage available
- Buildings owned by the borrower and included in the mortgage: C1 fire station 33 sqm, C2 annex 19 sqm, C4 garage 22 sqm, C5 mechanical workshop 281 sqm, C6 garage 25 sqm, C7 garage 49 sqm, C8 materials depot 69 sqm, C9 garage 24 sqm, C10 fire station 81 sqm, all dating from around 1970; the appraiser found most of them demolished or in unsatisfactory condition and attributes them a combined value of EUR 2,100
- Buildings not owned by the borrower: two dwellings on the same plot, C3 (118 sqm) and C11 (107 sqm), are registered in the ownership of VITIVINICOLA BASARABI S.A. and are not part of the security
- Title: acquired by notarial deed no. 1777 of 23 October 2023 following a public auction in the seller's insolvency; position C16 of the land book records that the land and the borrower's buildings were registered free of charges under art. 53 of Law 85/2006 and art. 91 of Law 85/2014. Historical notations from 2003 and 2007 (an attachment and a summons in enforcement files against the previous owner) remain visible in Part III of the land book; the current extract of 3 September 2026 shows no mortgage
- Valuation: EUR 180,600 (RON 920,000), of which land EUR 178,500 at EUR 26 per sqm and buildings EUR 2,100, by Sabo Marius Alexandru, ANEVAR member no. 15878, Fairvalue Consulting, report of 13 March 2026, market comparison approach for the land
Combined collateral value: EUR 418,700, against a facility of EUR 275,000: loan-to-value 65.68%, coverage 152%. The mortgages are registered in first rank in favour of the investors, represented by STOCKESTATE CROWDFUNDING S.R.L., at the notarial session at which the funds are released.
5. Market Analysis
Otopeni residential market. The Otopeni appraisal relies on the market comparison approach with three comparable houses in the same micro-location, adjusted to a range of approximately EUR 1,678 to EUR 2,367 per usable sqm for finished houses; the subject house under completion is valued at EUR 1,744.71 per usable sqm, in the lower part of that range, to reflect the works still to be executed. The appraiser describes supply in the Otopeni house segment as high and effective demand as medium and stagnating, constrained by access to financing. The vacant plot is valued at EUR 165.17 per sqm.
Murfatlar land market. The Murfatlar appraisal relies on four land comparables in Murfatlar, Valu lui Traian, Poarta Alba and Ovidiu, with asking prices between EUR 18 and EUR 27 per sqm before adjustments, and concludes at EUR 26 per sqm for the subject plot after a 5% deduction for the cost of clearing the demolishable buildings. The appraiser applied the market comparison approach for the land and the cost approach for the buildings, and cross-checked the result with an income approach. The pool of buyers for a 0.7 ha industrial-residential plot is narrower than for a residential house, and a forced sale would require a longer exposure period.
Sensitivity. A forced-sale discount of 20% on the combined collateral value of EUR 418,700 gives approximately EUR 335,000, which still covers the facility of EUR 275,000 at a loan-to-value of approximately 82%. A discount of 34% or more would bring the collateral value below the facility.
6. Financial Analysis
This is a working capital loan to an operating company, not a development project, so there is no projected sale price. The analysis covers the use of proceeds, the collateral coverage and the borrower's financial position as filed with ANAF.
Use of proceeds
| Item | Amount (EUR) | Share |
|---|---|---|
| Working capital of SELEX TRADING S.A. | 275,000 | 100% |
| Total facility | 275,000 | 100% |
The borrower has declared the destination of the funds as working capital for its real estate letting activity. No itemised budget has been provided to the platform.
Borrower financials, as filed with ANAF (RON)
| Indicator | 2023 | 2024 | 2025 |
|---|---|---|---|
| Net turnover | 15,345,194 | 11,339,387 | 22,650,679 |
| Net result | 1,468,703 | 40,730,769 | 5,050,561 |
| Total equity | 1,638,972 | 41,069,741 | 6,220,773 |
| Total debt | 101,143,931 | 218,086,327 | 377,710,195 |
| Total assets | n/a | 265,091,529 | 386,629,455 |
| Cash and bank | n/a | 4,146 | 2,545 |
| Average employees | n/a | 1 | 2 |
Structure of the balance sheet at 31 December 2025: intangible assets (trademarks and licences) RON 81.6 million, 21.1% of total assets; tangible assets RON 155.9 million, 40.3%, of which RON 74.1 million are fixed assets and property investments under construction; receivables RON 136.9 million, 35.4%. Liabilities are dominated by sundry creditors of RON 241.8 million and balances with affiliated entities of RON 43.1 million; bank debt is RON 23.7 million plus RON 4.1 million of accrued unpaid interest. Dividends of RON 40.4 million were declared in 2025, of which RON 12.5 million remained payable at year end and RON 9.7 million at 30 June 2026.
Turnover in 2025 consisted almost entirely of rental income (RON 22.4 million), of which 36% was booked in December 2025. Other operating income of RON 15.9 million in 2025 was made up chiefly of indemnities and penalties, also booked in December.
First half of 2026 (trial balance at 30 June 2026, unaudited): rental income of RON 2,872,444, indemnities and penalties of RON 6,551,383, interest income of RON 2,958,436; interest expense of RON 4,633,945; net profit of RON 166,431. Cash and bank balances of RON 3,458. Rental income in the first half of 2026 ran at an annualised rate approximately 74% below 2025.
Key ratios at 31 December 2025
| Ratio | Value |
|---|---|
| Debt to equity | 60.7x |
| Debt to total assets | 97.7% |
| Current ratio | 0.86 |
| Cash to current liabilities | 0.002% |
| Facility as share of total liabilities at 30 June 2026 | 0.3% |
The reference exchange rate used on this page is RON 5.2557 per EUR, the BNR rate of 11 September 2026.
Cost of the facility
The borrower pays a fixed interest of 16.00% per annum on the facility. Investors receive between 10.00% and 16.00% per annum according to the amount invested; the difference between the borrower rate and the investor rate is the platform's remuneration. No fee is borne by investors.
Repayment source
The principal is repaid in a single instalment at the end of month 6, on 15 April 2027. The borrower names three channels, in no fixed order: rental income from its property portfolio, the sale of one or more of its properties, and refinancing from a bank or non-bank lender. None of these channels is contractually secured at the date of this page. The realisation of the mortgaged properties is the fallback.
7. Funding and Investment Opportunity
| Parameter | Value |
|---|---|
| Facility in this offer | EUR 275,000 |
| Pre-committed amount | none |
| Campaign period | 24 September 2026 to 15 October 2026 |
| Loan term | 6 months from the close of the campaign on 15 October 2026, maturity 15 April 2027 |
| Remuneration interest rate to investors | Progressive, from 10.00% to 16.00% per annum, fixed at signing according to the invested amount |
| Floor rate and interest pool | 10.00% floor rate plus an interest pool of 6.00 percentage points |
| Interest rate paid by the borrower | 16.00% per annum |
| Interest rate after loan extension | 18.00% per annum, fixed |
| Penalty interest rate | 20.00% per annum, fixed |
| Cashback | None |
| Investor fees | None |
| Interest payment frequency | Monthly, at the end of each calendar month |
| Principal repayment | Single instalment at maturity |
| Day-count convention | 30/360 |
| Minimum investment ticket | EUR 100 |
| Borrower | SELEX TRADING S.A., sole owner of the mortgaged properties |
| Security instrument | First-rank mortgages over CF 117529 Otopeni (house and 230 sqm plot), CF 121186 Otopeni (247 sqm plot) and CF 100017 Murfatlar (6,866 sqm plot and outbuildings) |
| Collateral basis | Independent appraisals by ANEVAR members: report no. 56 of 16 June 2025 (Otopeni) and report of 13 March 2026 (Murfatlar) |
| Underlying valuation | EUR 418,700, of which Otopeni EUR 238,100 and Murfatlar EUR 180,600 |
| Effective collateral coverage | 152% |
| Loan-to-value | 65.68% |
| Mortgage timing | Registered at the notarial session at which the funds are released |
| Disbursement mechanism | Single drawdown at the notarial closing, after registration of the first-rank mortgages, against a land register extract for authentication issued on the day of signing |
How the progressive rate works
Each investment receives its own annual contract rate, fixed at the moment it is signed. The rate starts at the 10.00% floor and rises within the 6.00 percentage point interest pool according to the amount invested, following the rate bands published on this campaign page. The borrower pays 16.00% per annum on the whole facility; the part of the pool not allocated to investors is the platform's fee. Once signed, the rate of an investment does not change for the life of the loan.
Security mechanics
The three properties are free of mortgages at the date of this page, according to the land register extracts on file. At the notarial closing, in a single session, the first-rank mortgages in favour of the investors are registered over the three properties and the funds are released to the borrower. The borrower will insure the house in Otopeni and assign the insurance indemnity to the investors' representative. The responsible Romanian notary is designated at the closing of the transaction.
Platform
stock.estate is a European Crowdfunding Service Provider licensed by the Autoritatea de Supraveghere Financiara of Romania under licence PJR28FSFPR/400002, operating under Regulation (EU) 2020/1503 (ECSPR).
8. Risks and Mitigations
-
Borrower leverage and liquidity. At 31 December 2025 the borrower reported total debt of RON 377.7 million against equity of RON 6.2 million, a debt-to-equity ratio of 60.7x, and cash of RON 2,545; at 30 June 2026 cash was RON 3,458. The company cannot service or repay this loan from its cash balances. Mitigation: the loan is sized on the collateral rather than on the borrower's cash flow, is secured by first-rank mortgages over three properties with a combined appraised value of EUR 418,700, and represents 0.3% of the borrower's total liabilities.
-
Concentration and volatility of income. Rental income of RON 22.4 million in 2025 was 36% booked in December, other income of RON 15.9 million consisted of indemnities and penalties booked in December, and rental income in the first half of 2026 ran approximately 74% below the 2025 level on an annualised basis. Mitigation: the principal is repaid at maturity from rental income, asset sales or refinancing, and the term is short, 6 months.
-
Other creditors and dividends. Sundry creditors of RON 240.6 million and balances with affiliated entities of RON 86.9 million at 30 June 2026 are not documented to the platform as to counterparty and maturity, and dividends of RON 9.7 million remained payable to the shareholder. These obligations compete with the loan for the borrower's resources. Mitigation: the investors hold a real security ranking ahead of unsecured creditors over the three mortgaged properties, which are free of charges.
-
Litigation and enforcement history. Public records show 22 court files involving the borrower, of which 13 concern intellectual property (trademarks) and three opened in 2025 concern a payment order and two objections to enforcement, the borrower being the debtor or the objector. A creditor holding an enforceable title could pursue the borrower's assets. Mitigation: the mortgaged properties are free of charges and the investors' first-rank mortgages are registered before any funds are released, so a later attachment would rank behind them.
-
Collateral coverage close to the platform minimum. Coverage of 152% leaves little margin: a decline of 34% or more in the realisable value of the collateral would bring it below the facility. Mitigation: the collateral is spread over three properties in two different markets, and the Otopeni house and plot, EUR 238,100, alone cover 87% of the facility.
-
Condition and age of the appraisals. The Otopeni house was approximately 75% complete, without interior finishes, at the inspection of 5 June 2025, and the Otopeni appraisal dates from June 2025, fifteen months before this offer; the Murfatlar appraisal dates from March 2026. Both were commissioned in the context of earlier financing applications by the borrower. Mitigation: both reports were prepared by ANEVAR members under the Romanian valuation standards, the Otopeni valuation applies a discount to the finished-house comparables for the unexecuted works, and the Murfatlar valuation attributes almost no value to the buildings.
-
Murfatlar plot: third-party buildings and legacy notations. Two dwellings on the Murfatlar plot belong to VITIVINICOLA BASARABI S.A. and are outside the security, which may reduce the liquidity of the plot in a forced sale; Part III of the land book still displays notations from 2003 and 2007 relating to enforcement against the previous owner. Mitigation: position C16 of the land book records the borrower's land and buildings as registered free of charges under the insolvency law, the appraiser's value of EUR 26 per sqm is at the level of the comparable industrial-residential plots in the area, and the Murfatlar property represents 43% of the collateral value.
-
Repayment risk. Principal is repaid in a single instalment at maturity rather than amortised, and none of the named repayment channels is contractually secured. Mitigation: first-rank mortgages over three properties as the fallback, and a short term of 6 months.
-
Variable rate at signing. The contract rate of each investment depends on the amount invested and on the conditions in force at signing, so two investors in the same campaign may receive different rates. Mitigation: the rate is displayed before signing, is fixed for the life of the loan once signed, and can never fall below the 10.00% floor.
-
Currency risk. The loan is denominated in euro while the borrower's income is predominantly in Romanian lei. A depreciation of the leu increases the local-currency cost of servicing and repaying the facility. Mitigation: the term is short and real estate prices in Romania are commonly quoted in euro.
-
Illiquidity. Loans concluded through the platform are not admitted to trading on a regulated market and no secondary market is guaranteed. Investors should be prepared to hold the investment to maturity.