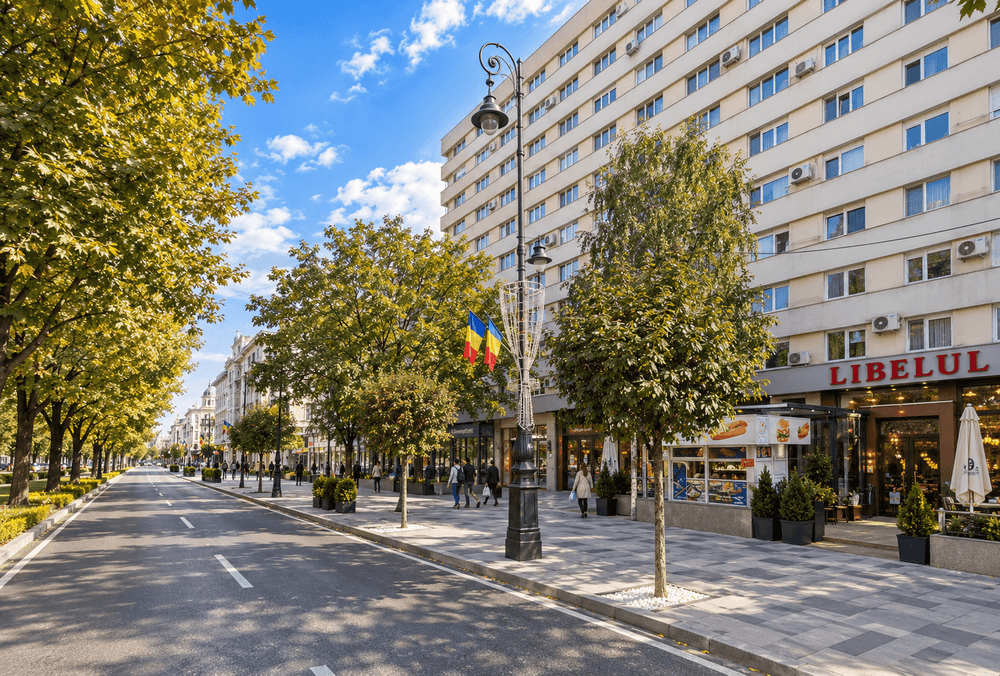

Bulevardul Republicii 49-53, Arad
- Type of property
- Residential
- Location
- Arad, Arad County, Romania
- Loan duration
- 12 months
- Interest rate
- 10-16% / year
- Payment
- Monthly
- End date
- Oct 12, 2026
- Invested
- € 157 000
- Loan to value
- 47.77 %
- Collateral
- Real estate mortgage
Reimbursement progress: 2%
1. Executive Summary
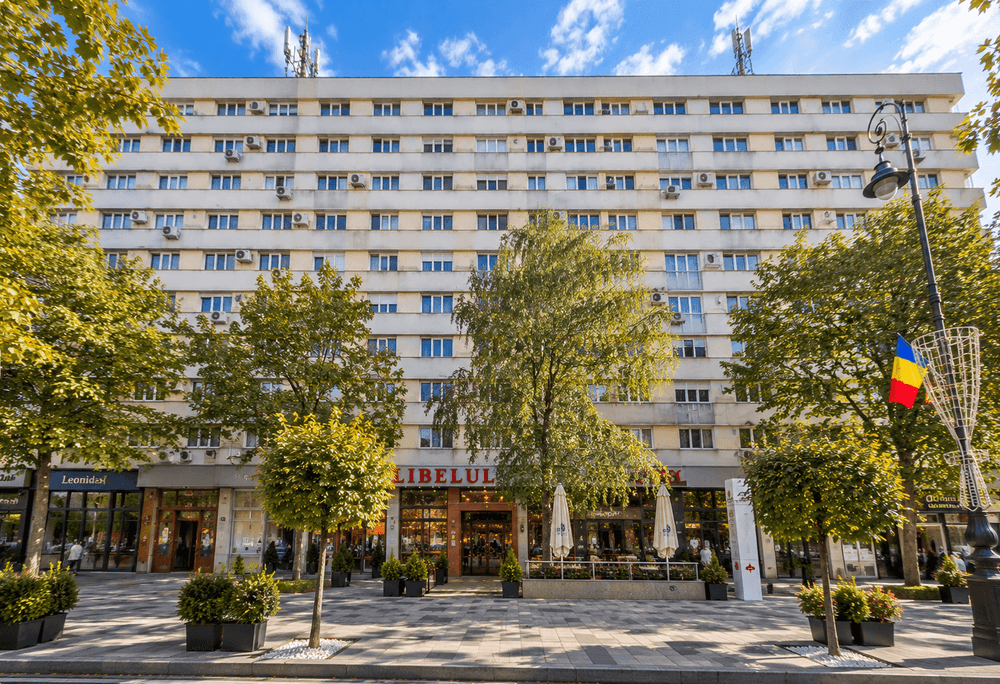
XEDORA S.R.L., an Arad-based company active in the purchase, renovation and resale of residential property, is acquiring four apartments (two 2-room and two 3-room units, 219.41 m² usable in total) in the ultracentral "Libelula" residential block at Bulevardul Republicii 49-53, Arad, for €235,000. The company plans an interior renovation budgeted at €40,000, followed by the resale of all four units at a projected aggregate price of €370,000. This campaign raises €150,000 to part-finance the acquisition, with the developer contributing €85,000 of the purchase price plus the full renovation budget and all transaction costs from its own funds. The loan runs for 12 months, pays monthly interest at a progressive rate of 10.00% to 16.00% p.a. depending on the amount invested, and repays principal at maturity or earlier, partially, as units are sold. The loan is secured by a first-rank mortgage on all four apartments, registered contextually with the acquisition deed. The four units have an independent ANEVAR market value of €274,000 in their current, unrenovated condition. Adding the €40,000 renovation budget gives a collateral basis of €314,000, a loan-to-value of 47.8% and a collateral coverage of 209%.
2. Location Analysis
Arad is the seat of Arad County in western Romania, on the Mureș river, with a population of approximately 145,000 (2021 census). The city lies on the A1 motorway corridor linking Bucharest to the Hungarian border at Nădlac (about 50 km) and Central Europe. It is approximately 55 km from Timișoara and has its own international airport. The independent valuation report describes the local economy as developed and diversified. It lists industry, commerce and logistics as the main sectors, supported by Arad's position on the principal transport routes between Romania and Central Europe.
The property is located on Bulevardul Republicii (formerly Bulevardul Revoluției), the city's main central boulevard, in the ultracentral area. According to the valuation report, the immediate area is a mixed, predominantly residential zone with P+4 and P+10 residential blocks, single-family houses and commercial premises. Public transport, shops, schools and universities, medical facilities, banks and parks are all nearby. The area is fully connected to electricity, water, sewerage, natural gas, district heating and telecommunications networks.
Population density and average age in the area are described by the valuer as stable. Demand for the ultracentral segment is driven by owner-occupiers with average incomes who have access to mortgage financing.
3. Developer Profile
- Legal entity: XEDORA S.R.L., CUI 48351839, registered with the Trade Register under J2023000934029 on 19.06.2023, registered office in Arad
- Activity: purchase, renovation and resale of own residential property (CAEN 6810), carried out together with finishing works (CAEN 4334)
- Shareholding: two Romanian individual shareholders (60% / 40%); the majority shareholder is also the sole director
Since incorporation, the company has bought, renovated and resold residential units in Arad. The shareholders have completed similar transactions before. Filed results:
| Year | Net turnover (RON) | Net profit (RON) | Total equity (RON) |
|---|---|---|---|
| 2023 (first 6 months of activity) | 188,266 | 28,076 | 28,276 |
| 2024 | 1,045,036 | 119,683 | 147,959 |
| 2025 | 631,762 | 36,593 | 169,552 |
| H1 2026 (trial balance 30.06.2026) | 244,565 | 12,492 | n/a |
At 30.06.2026 the company held one residential unit in inventory (book value RON 237,694) and cash of about RON 111,000. It also carried shareholder loans of RON 221,309. A short-term bank facility of RON 136,718 was fully repaid during 2026. Public records checked on 19.09.2026 show:
- no tax arrears with ANAF
- no court proceedings
- no insolvency filings
- no movable-asset security registered in the RNPM/AEGRM
4. Project Overview
Property: four apartments in a S+P+10 residential block at Bulevardul Republicii 49-53, Arad. The block was built around 1980 and thermally modernised in 2025, according to its energy certificate. It has a lift, a reinforced concrete frame, a thermal insulation system and individual gas boilers in each apartment. The valuer rates the building's overall condition as good. The land is state-owned, with the units holding an undivided share of it.
| Unit | Staircase / floor | Rooms | Usable area | Built area | Land share | Current market value (ANEVAR) | Projected sale price |
|---|---|---|---|---|---|---|---|
| Ap. 1 | Sc. C, floor 1 | 3 | 65.93 m² | 75 m² | 11/1250 | €79,000 | €100,000 |
| Ap. 16 | Sc. C, floor 4 | 3 | 62.14 m² | 75 m² | 11/1250 | €74,000 | €100,000 |
| Ap. 10 | Sc. B, floor 3 | 2 | 45.67 m² | 53 m² | 7/1250 | €63,000 | €85,000 |
| Ap. 38 | Sc. A, floor 10 | 2 | 45.67 m² | 53 m² | 7/1250 | €58,000 | €85,000 |
| Total | 219.41 m² | 256 m² | €274,000 | €370,000 |
Land Registry: CF 301118-C1-U96, U99, U101 and U103, Arad. The land registry extracts and the sale promise show that the units are free of mortgages or other encumbrances. The units are vacant.
Current condition (valuation report):
- semi-detached layout, comfort category I and II
- PVC exterior joinery, metal entrance doors
- tiles in wet areas, laminate or wooden flooring in rooms
- individual gas boiler with radiators
- finishes rated lower-to-medium quality, requiring renovation
Planned renovation (cost estimate "Proiect Libelula", RON 160,000 total; budget retained at €40,000 including contingency):
- complete refurbishment of the bathroom in each unit, including sanitary installations
- new laminate flooring and skirting boards
- wall repairs and preparation, full repainting
- new ceramic tiling where required
- servicing of the electrical installation, with new sockets and switches
- all materials and labour included
Timeline:
- renovation: 3 months from acquisition
- sales: expected to complete within 6 months of acquisition
- loan term: 12 months, which leaves a 6-month buffer after the planned sales window
Permits: the works are interior finishing and do not require a building permit.
Energy class: the building was thermally rehabilitated in 2025. The energy performance certificates for the individual units will be issued before resale.
5. Market Analysis
Asking prices for apartments in Arad average about €1,250-1,330/m² usable in 2026:
- hartapreturilor.ro: median €1,251/m², with prices stable over the last month
- vdi.ro, Q3 2026: typical 2-room apartment around €69,000, or about €1,271/m², down 4.3% year-on-year
- acasaarad.ro, week 31 of 2026: weighted average of €1,329/m² across new listings
City averages vary significantly by zone. The same acasaarad.ro weekly report gives an average of €1,685/m² for the Ultracentral zone, against €1,318/m² for Central and €1,243/m² for Vlaicu.
The valuation report describes the local market as in relative equilibrium, with stagnating demand, stable to rising prices and increasing construction costs. It also notes that most listings in the area are older, unrenovated units. Its comparables for the subject units are ultracentral apartments in similar P+10 and P+4 blocks, asking €69,900 to €95,000 (€1,371 to €1,662/m²).
Monthly rent for a 2-room apartment in Arad is about €350 (vdi.ro, Q3 2026). This gives an alternative use for any unit not sold within the planned window.
Pricing rationale. The projected aggregate sale price of €370,000 on 219.41 m² usable implies a blended €1,686/m². This is above the city-wide average but in line with the ultracentral zonal average of €1,685/m²:
- Zone: the property is on the city's main boulevard, in the highest-priced zone of Arad, where the relevant benchmark is the ultracentral average rather than the municipal one.
- Renovated vs. unrenovated stock: the averages quoted above are built almost entirely on older apartments with original or worn finishes. The valuation report notes that the listings available in the area are mainly older units, and it rates the subject units' own current finishes as lower to medium, requiring renovation. After the works, every unit will be sold fully refurbished, with a new bathroom, new flooring, new finishes and serviced installations. The block itself was thermally rehabilitated in 2025. Renovated units in this building therefore compete with a small pool of ready-to-move-in stock, not with the unrenovated stock that sets the averages. The difference in value is visible in the valuation itself: the as-is values of €58,000 to €79,000 carry the valuer's deduction for the cost and time of refurbishment, which the planned works remove.
- Product mix: the 3-room units are priced at €1,517/m² (Ap. 1) and €1,609/m² (Ap. 16), below the ultracentral average. The 2-room units are priced at €1,861/m², reflecting the higher price per m² that smaller, more liquid units typically achieve.
- Asking vs. transaction prices: the market data above are asking prices, which the acasaarad.ro report estimates at 5-12% above final transaction prices. Section 6 therefore also shows the result under a 10% lower sale price.
Overall, Arad's residential prices remain below those of Timișoara and Cluj-Napoca, the main regional reference markets in western and north-western Romania.
6. Financial Analysis
| Item | Amount (€) | €/m² usable |
|---|---|---|
| Acquisition price (4 units) | 235,000 | 1,071 |
| Brokerage fee payable at closing (4.5% of price) | 10,575 | |
| Notary and land registry costs (estimate) | 3,500 | |
| Renovation budget (incl. contingency) | 40,000 | 182 |
| Subtotal: direct project cost | 289,075 | 1,318 |
| Estimated cost of external financing (interest at 16.00% p.a. on €150,000 for 12 months and financing costs) | 30,000 | |
| Total project cost | 319,075 | 1,454 |
| Projected aggregate sale price | 370,000 | 1,686 |
| Projected gross profit (excluding financing) | 80,925 | 369 |
| Projected net profit (including financing) | 50,925 | 232 |
| Margin | Gross (excl. financing) | Net (incl. financing) |
|---|---|---|
| On cost | 28.0% | 16.0% |
| On revenue | 21.9% | 13.8% |
| Per m² usable | €369/m² | €232/m² |
Notes and sensitivity:
- The financing cost assumes the loan runs the full 12 months. If the units sell within 6 months, as planned, and principal is repaid as sales close, the interest cost is about half, and net profit rises accordingly.
- Resale brokerage costs, if any, are not included.
- Sale price 10% lower (€333,000): projected net profit of about €13,925, and the loan is still repaid in full.
- Break-even: sales at the ANEVAR current market value (€274,000) repay the loan (€150,000) with €124,000 to spare, but would not recover the developer's equity in full.
Renovation cost check. The contractor estimate totals RON 160,000, about €30,500 at the valuation report's exchange rate of RON 5.2460/€:
- 2-room units: RON 35,000 each
- 3-room units: RON 45,000 each
The budget retained for this analysis, €40,000, includes a contingency of about 31%.
Repayment source: proceeds from the sale of the four renovated units. See Section 7.
7. Funding and Investment Opportunity
| Parameter | Value |
|---|---|
| Loan amount (this campaign) | €150,000 (minimum = target = maximum) |
| Pre-committed amount | none |
| Campaign period | 25 September 2026 to 15 October 2026 |
| Developer equity | €85,000 of the purchase price (of which €20,000 already paid as deposit), plus the €40,000 renovation budget, the €10,575 brokerage fee, and notary and land registry costs, from own funds: about €139,000, plus all interest and financing costs |
| Loan term | 12 months from the close of the campaign on 15 October 2026, maturity 15 October 2027 |
| Remuneration interest rate to investors | Progressive, from 10.00% to 16.00% per annum, fixed at signing according to the invested amount |
| Floor rate and interest pool | 10.00% floor rate plus an interest pool of 6.00 percentage points |
| Interest rate paid by the borrower | 16.00% per annum |
| Interest rate after loan extension | 18.00% per annum, fixed |
| Penalty interest rate | 20.00% per annum, fixed |
| Cashback | None |
| Investor fees | None |
| Interest payment frequency | Monthly, at the end of each calendar month |
| Principal repayment | At maturity. Partial early repayments as each unit is sold, with partial release of the mortgage on the unit sold |
| Day-count convention | 30/360 |
| Minimum investment ticket | €100 |
| Security | first-rank mortgage on all four apartments (CF 301118-C1-U96, U99, U101, U103, Arad), in favour of STOCKESTATE CROWDFUNDING S.R.L. as security agent |
| Collateral basis | independent ANEVAR appraisal no. 598/10.08.2026, current pre-renovation market value €274,000, plus the €40,000 renovation budget funded by the developer: €314,000 |
| Loan-to-value | 47.8% (€150,000 / €314,000) |
| Collateral coverage | 209%, against a platform minimum of 150% |
| LTV on the pre-renovation appraisal alone | 54.7% (€150,000 / €274,000), coverage 182.7% |
| LTV on projected sale value | 40.5% (€150,000 / €370,000) |
| Mortgage timing | registered contextually with the notarised sale deed, at the same notary session in which XEDORA S.R.L. acquires the units |
| Disbursement mechanism | funds are paid at the notarial closing directly into the seller's bank account, as part of the acquisition price. No funds pass through the borrower before the mortgage is signed |
How the progressive rate works
Each investment receives its own annual contract rate, fixed at the moment it is signed. The rate starts at the 10.00% floor and rises within the 6.00 percentage point interest pool according to the amount invested, following the rate bands published on this campaign page. The borrower pays 16.00% per annum on the whole facility; the part of the pool not allocated to investors is the platform's fee. Once signed, the rate of an investment does not change for the life of the loan.
Capital stack and funding plan
The acquisition is funded €150,000 by this loan and €85,000 by the developer. The developer also funds the renovation, transaction costs and all financing costs, including interest, from its own resources. The sale promise sets 16.10.2026 as the deadline for the notarised sale, so the campaign closes on 15.10.2026. The loan is the only external financing in the project. No further platform tranche is planned. Repayment channels, in order of preference:
- sale of the four renovated units, with principal repaid pro rata as each sale closes
- developer equity and operating cash flow, including other residential units in the company's inventory
- rental of unsold units, or bank refinancing of the remaining balance
Platform
stock.estate is a European Crowdfunding Service Provider licensed by the Autoritatea de Supraveghere Financiara of Romania under licence PJR28FSFPR/400002, operating under Regulation (EU) 2020/1503 (ECSPR).
8. Risks and Mitigations
- Market risk. Sale prices or sale times may differ from projections; the valuer describes the local market as a buyer's market with stagnating demand. Mitigation: the blended projected price matches the ultracentral zonal average, and a 10% lower sale price still repays the loan in full. The loan is sized at 47.8% of the collateral basis including renovation, and at 54.7% of the unrenovated appraised value alone.
- Construction risk. Renovation costs or duration may exceed the estimate. Mitigation: the budget retained (€40,000) exceeds the contractor estimate by about 31%. The works are interior finishes only, the developer carries out this type of work as part of its core activity, and the renovation is funded from the developer's own resources.
- Repayment risk. Delays in sales could postpone repayment. Mitigation: the plan foresees sales within 6 months against a 12-month term. Principal is repaid unit by unit as sales close, and monthly interest is paid from the developer's own funds. Unsold units can be rented or refinanced.
- Funding-completion risk. The campaign must close before the 16.10.2026 deadline in the sale promise. Mitigation: the campaign is all-or-nothing at €150,000. If the target is not reached, all investor funds are returned in full.
- Collateral and disbursement risk. Investor capital could be exposed if funds were released before the security is in place. Mitigation: funds are paid at the notarial closing directly to the seller, and the first-rank mortgage is signed and filed for registration in the same session. There is no unsecured-capital window.
- Regulatory and permitting risk. Changes to the authorisations required for the works. Mitigation: the works are interior finishing works that do not require a building permit, and the units are existing residential apartments with clear title.
- Concentration risk. The borrower is a small company with a single project of this size. Mitigation: security is spread across four separately registered and separately saleable units, each covered by its own first-rank mortgage.
- Variable rate at signing. The contract rate of each investment depends on the amount invested and on the conditions in force at signing, so two investors in the same campaign may receive different rates. Mitigation: the rate is displayed before signing, is fixed for the life of the loan once signed, and can never fall below the 10.00% floor.
- Currency risk. The loan is denominated in euro while the borrower operates in Romanian lei. Mitigation: residential property in Arad, including the sale prices in this plan, is quoted and transacted in euro.
- Illiquidity. Loans concluded through the platform are not admitted to trading on a regulated market and no secondary market is guaranteed. Investors should be prepared to hold the investment to maturity.